
Not a week goes by without another data center FUD. We’ve already explained in depth why moratoriums don’t have as much impact as you might think.. Despite this, many still have little understanding of the pace of development of AI data centers globally. The other week, Altimeter’s Brad Gerstner showed our data on the All-In Podcast and said that “SemiAnalysis’s forecast of +43 GW in 2027 is too aggressive” and that he thought only about 25 GW would be built, or almost half our figure, based on his “gut feeling.” But let’s not rely on intuitions.
It’s very tempting to give in to FUD given all the constraints of building a data center: energy, labor, supply chains, capital and more. But at SemiAnalysis, we care about truth, not stories. And here’s the truth for you: a picture, more than 24 GW of data centers in an advanced stage of construction, all delivered in 2027. Most of them are more than half complete, with outdoor cooling and electrical equipment already installed. This represents only 40 campuses, a tiny fraction of the hundreds of sites in an advanced stage of construction. We track them all and for complete granularity use our Data center industrial model.
Of course, there are many challenges and shortages. Behind these images hide, among other things, labor problems, delays in the supply chain, difficulties in fundraising. We have written in depth about Modular Data Centers and WorkforceData Center Electric systems, Cooling systems, A power behind the counterTHE Constraints of the American networkAnd Financial support from the Nvidia ecosystem. But the fact is simple: gigantic projects are simply built, and many are completed on time. For example, look at what Crusoe built in Abilene, what AWS built in Indiana, or the giant QTS/Microsoft facility in Georgia. These are the sites that produced SOTA technology like GPT-6 and Fable 5.5. In the future, despite all constraints, an increasing number of giant sites continue to be built, as our Top 40 shows.
If you ask any data center builder, they will tell you how difficult it is, how some workers don’t show up, how suppliers are delayed and many other problems. This is all correct. That’s why we’ve managed to expose countless data center delays and call out developer deadlines that seem too aggressive in our data center model, including the Oracle New Mexico Site Delay Force Majeure in April. To be honest, +50 GW is basically the cumulative global data center market through 2024, built in one year! But our Data center industrial model accommodates all of this and still points to a significant acceleration in data center capacity in 2027. So what are we seeing that others can’t?
Let’s go further. We will explore the following topics in this report:
SemiAnalysis Proprietary Leading Indicators: We will display an overview of our proprietary data supporting our forecasts, such as self-build starts and data center rentals (in MW and USD). Year to date, just under $1 billion in binding/non-cancelable data center leases signed – this is the key to supporting our aggressive forecasts for 2027-2028.
The form of the project: how to support +50 GW in a single year? Where, what design, what power solutions?
The “real” question: are we going to face data center oversupply? As we explained in The great silicon shortagedata centers and power may be just the tip of the iceberg, with memory and logic possibly becoming the #1 new constraint in 2027-2028.
Overall, we are very excited about 2027. The natural implication of this acceleration will be significantly greater compute offerings. This means cheaper and smarter AI, a faster rate of progression of the AI model, and a likely acceleration of hardware revenue for major AI labs and other token providers. This also means unthinkable investment figures. Reflexively, rates will have to rise to allow construction from a capital demand perspective. Let’s go!
Today, we want to look at two crucial indicators that give us great confidence in our forecasts for 2027. The first concerns quarterly self-build construction starts. To accurately forecast US hyperscalers, we track the exact construction progress of each building. And the conclusion is simple: American hyperscalers have never launched so much data center construction. Every quarter, we monitor the number of MW that start construction, and this number becomes parabolic, driven in particular by two hyperscalers. If you want to know who or follow the granularity of our data, subscribe to our Data center industrial model.
The second indicator is Datacenter Leasing. We’ve talked about this a lot in previous reports, but to quickly recap: given the capital intensity of building multi-hundred MW data centers, developers typically only spend 5-10% of project capital without a customer. They need a “pre-lease” to finance and develop the entire project. This is typically a 15-20 year contract, with a TCV of $30-50 billion per GW. Check out our HPC rental tracking as part of the Data Center Model to delve into the real contract economy.
As such, tracking these leases is a key leading indicator, as it leads to increases in debt, which themselves lead to the actual construction. One of the main reasons why data center growth in 2026 is not “that” high compared to 2025 is that quarterly data center rentals remained relatively stable between the second half of 2023 and the first half of 2025. Of course, the main reason was Microsoft’s data center freeze, which we denounced before anyone else in December 2024 for Data Center Model Subscribers: the Redmond giant single-handedly led the leasing market in 2023 and 2024, then took a break, and others could only pick up what was left behind.
Since the second half of 2025, things have changed radically. Oracle ushered in the era of gigantic leases, having closed around 4.5GW of data center computing capacity across three sites between August and October 2025. Everyone else followed, and the pool of buyers has never been wider, with Meta, AWS, Microsoft, Google, Nvidia, AMD, Anthropic and OpenAI all seeking GW-scale leases. There is also a long list of Neoclouds signing agreements at the scale of around 100 MW.
In U.S. dollars, that means unprecedented rental value that builders can use to leverage debt. In 2026 alone, we have identified over $1 trillion in lease value that has been signed and closed.. This trillion supports the construction of a gigantic data center in 2027-2028. Our new Model of calculation, capital and markets now tracks all debt increases and can confirm that most of this debt has been lifted.
Monitoring all these leading indicators allowed us to anticipate, before anyone else, the upcoming surge in orders from numerous industrial suppliers such as Vertiv, ABB, Sterling Infrastructure. View our industry model for in-depth coverage. However, the challenge now goes from ordering to delivery. And resources have obviously become limited, as energy, labor, and simple regulatory costs represent enormous burdens for developers. But the industry quickly responded by innovating.
The first step is to simplify data center design. Below we show how Google has modularized its electrical architecture, removing a significant amount of exterior wiring requiring on-site assembly, and replacing them with prefabricated electrical modules. We track all equipment changes (including suppliers) for data center design and forecast orders in our Industrial model
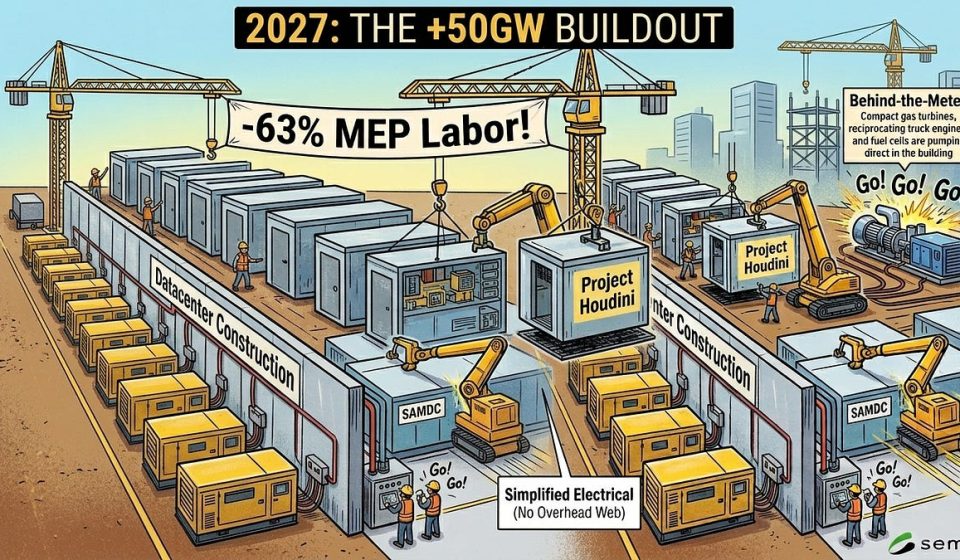
Others opted for more radical design changes. An example is Meta with its tent design, which we revealed exclusively more than a year ago. AWS is another that has significantly simplified its shell design and launched a new rapid design called “SAMDC”. Data halls are also increasingly prefabricated, an effort called Project Houdini at AWS. Construction times are now less than 10 months. Hence our “LEGO Data Centers“Headline for the modular movement, you literally drop them in and go, and it allows MEP labor (7-11 months of labor) to drop by up to 63%! We will have an in-depth analysis of 2027 construction labor soon.
In addition to large-scale self-build, data center developers promoting prefabricated designs have also seen remarkable success. DayOne is probably the best example. With a total of around 3 GW leased since their first transaction in early 2023, the Singaporean company is a rocket in terms of construction speed. While traditional developers have build times longer than 18 months, DayOne has reduced that time to around 9 months, which has been key to signing huge deals with Firmus, OpenAI, and Nvidia.
Another central problem is that of power, and again we believe that the problem is largely solved. We were the first to talk about all issues related to power, since March 2024 and subsequently given the network margin will turn negative at the end of 2027. This ended up leading AI Labs and hyperscalers to build their own power plantsbetter known as behind-the-meter generation, bypassing grid interconnection delays of 5 to 10 years. And while incumbent turbine players like GEV quickly faced production bottlenecks, the industry quickly responded and we have since seen an increase in the number of new OEMs and solutions supplying the market. From fuel cells to truck engines to retrofitted turbines, the problem of power generation has largely been solved.
In addition, development is now diversifying geographically. This naturally circumvents the labor, power, and (in some countries) licensing constraints of the United States. And as shown below, growth outside the US accelerates sharply in 2027, and we expect it to gain significant market share in 2028, largely driven by US challenges.
Gn bussni