
Protesters gather for a student demonstration at Place de la Bastille with a view of the Colonne de Juillet monument in Paris, October 8, 2026, as part of a national protest movement against learning conditions.
Simon Wohlfahrt | Afp | Getty Images
As France’s economic and political difficulties deepen, investors are wondering whether the country’s debt problems risk contaminating the rest of the euro zone.
The markets are sounding the alarm on the second largest economy in the euro zone. THE euro remained under pressure, falling almost 5% against the dollar since the start of the year.
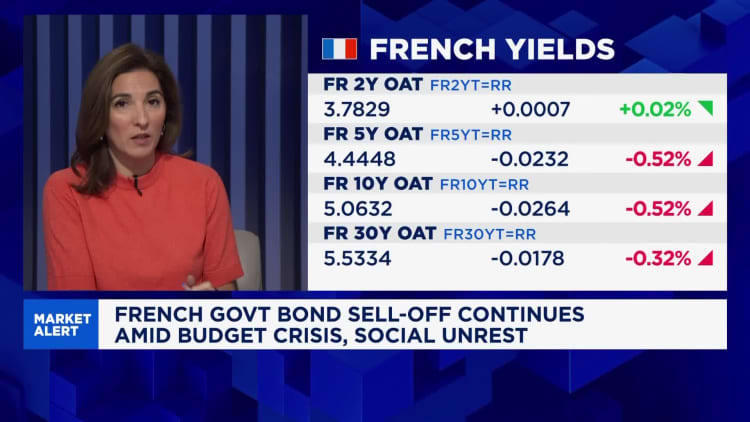
France’s benchmark borrowing cost, the yield on its 10 year depositexceeded 5% for the first time since 2002 this week before rising sharply.

Meanwhile, the spread between French and German 10-year bond yields – a closely watched measure of distress – rose above 170 basis points on Thursday for the first time since the euro zone debt crisis of the early 2010s. The cost of insuring the French government against default, as measured by credit default swaps, is also the highest since that period.
Contagion to the Eurozone
The big concern is fragmentation, when countries that share a currency face very different borrowing costs, adding to market stress and risking spiraling debt repayments for the worst-hit countries.
As the eurozone sovereign debt crisis of the early 2010s showed, market tensions in one country can spread quickly across economies that share a currency and central bank but maintain separate fiscal systems. The crisis started in Greece before spreading to countries like Portugal, Ireland, Italy and Spain.
Governments were expected to rescue struggling banks, which held large sums of sovereign debt, creating a vicious cycle.
The crisis only eased after rescue programs linked to sweeping austerity measures, and ECB President Mario Draghi pledged in 2012 to do “whatever it takes” to preserve the euro.
Economists warn that a new vicious cycle is being created – not just in France but in major economies from the US to the UK – as investor concerns over rising public debt drive up yields and interest costs, which in turn increases the debt burden.
A slowdown in bond purchases raises “the specter that the government will be forced to default because it simply does not have the liquidity to pay the interest and principal on its debt,” Nobel laureate Paul Krugman wrote in an Oct. 8 blog.
“Fear of default then leads to even more capital flight, which increases default and interest rate fears,” he said.
The risks linked to France’s debt
France, in particular, has one of the highest deficit-to-GDP ratios of the 21 eurozone countries and a growing national debt. Its economy has slowed to the point that the government has reduced its growth forecast for 2026 to just 0.5%.
These fiscal tensions come as political volatility and social unrest raise doubts about the government’s ability to implement measures to stabilize public finances.

“We are deep in crisis in France,” Carsten Brzeski, global head of macroeconomic research at ING and chief euro zone economist, said by email.
“There is no risk of an imminent liquidity problem for the French government but the lack of confidence in bond markets and the current crisis should ultimately create a high sense of urgency in Paris.”
John Stopford, head of multi-asset income at Ninety One, said France has gone from being a core or semi-core European country for bond investors to increasingly being seen as a periphery, which he called “bizarre” given France’s history relative to the EU and its economic power on the continent.
“As investors, we have simply chosen at this time to avoid virtually all non-essential European countries. The situation is too fluid and there is too much uncertainty to really want to get involved,” Stopford said in a conference call.
Why 2026 is different
Still, analysts CNBC spoke with largely agree that the reforms mean that even if the market behaves similarly to the post-financial crisis period, the risk of contagion this time around remains limited.
Ninety One’s Stopford said spreads would likely need to trade “in the 200s” before the situation was widely seen as a full-blown crisis – but, he added, that the situation in France “doesn’t look great”.
“French spreads are now wider than they were at the height of the peripheral crisis in the early 2010s, but they are still much narrower than the extreme levels we saw in Spain, Italy, Greece and Ireland at the time, so…I think the market assumption is that things will have to get worse before we get to the point where European institutions start looking at damage control,” he told CNBC.
BlackRock strategists noted that the current environment is “materially different” from that which preceded the 2011-2012 eurozone debt crisis, with the region now better equipped to withstand financial stress, but they added that “additional volatility and fallout remain possible.”
“The liquidation of French bonds illustrates how competition for capital is reshaping bond markets in a context of revised interest rates globally,” they write. “Rising government borrowing and AI-related investments are driving up financing costs, exposing borrowers with deteriorating fundamentals to greater scrutiny.”
George Lagarias, chief economist at Forvis Mazars, said France was already in a debt crisis, citing its debt-to-GDP ratio of 119% at the end of the second quarter of 2026 – close to Greece’s 128% at the end of 2009.
A fallout would result in a wider yield gap between France and Germany, followed by higher prices for credit default swaps – the cost of insuring debt, he said.

The gap between French and German 10-year bonds continues to widen
“Italy and Spain would experience higher borrowing costs and would have to reduce fiscal spending, which could spark political backlash in their own countries,” he told CNBC. “The European periphery would be under enormous pressure, even if its finances were much better than a few years ago.”
However, Lagarias said crucial structural differences minimize the risk of a broader fallout, comparable to that of the early 2010s, which he estimates at between 10 and 20 percent.
“Greece has a very bad trade deficit. France also has a trade deficit, but the numbers are much more benign,” he said by email.
He added that INSEE, France’s national statistics body, “probably wouldn’t lie about the deficit” and compared the situation to that of Greece.
In 2009, Greece sharply revised its budget deficit forecast, from 3.7% of GDP in the spring to 12.5% by October, undermining confidence in the reliability of its public finances and helping to accelerate the crisis.
“The (French) debt levels are worrying but known. The markets can cope with the known risks. They hate surprises,” added Lagarias. “What sank Greece was a deficit that suddenly turned out to be five times the official estimate. This catalyzed a crisis.”
Alex Everett, investment director for rates management at Aberdeen Investments, agreed that the current environment should be treated “primarily as a French risk rather than a systemic risk for the eurozone”.
“Compared to the early 2010s, the eurozone has stronger banks, greater integration and many tools designed to limit the risk of sovereign fragmentation,” he said. “I expect the contagion to be short-lived.”
Gn bussni