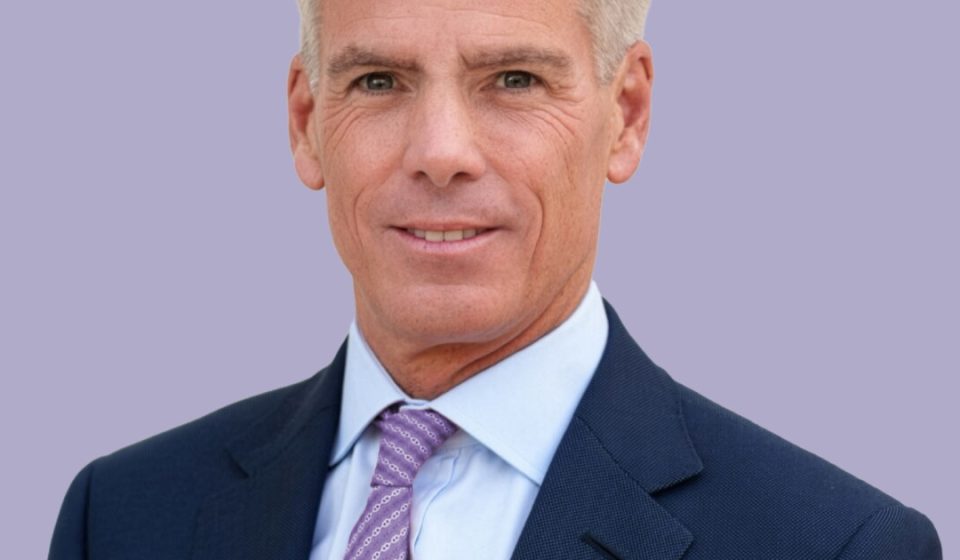

- Key insight: Mike Lyons, who took the CEO reins at Truist last month, announced several changes Friday that he said will make the bank more successful.
- What is at stake: The long-struggling superregional bank will have to act relatively quickly to satisfy its shareholders, who have been waiting for years for the underperforming bank to deliver on the promises it made seven years ago.
The new general director of
Content processing
In his first public remarks since his arrival
Lyon also recognized
Now is the time to change, starting with
“While I believe history and context are important and we have learned from them, we are where we are today and we know we can do better,” Lyons said during the bank’s third-quarter earnings conference call. “We are now firmly focused on the future and have the chance to move forward with enormous strengths. Above all, we do not need to reinvent
Analysts who cover
“From a strategic standpoint, I love the tonal contrast at the top,” Mike Mayo, an analyst at Wells Fargo Securities, told American Banker. “This is clearly a much more shareholder-oriented CEO,” whose early message focused on simplification, execution and growth to create shareholder value, he said.
Still, Lyons and his management team find themselves in a difficult situation, at least in the short term, Mayo said.
“Financially, progress will be difficult,” Mayo predicted. “They haven’t been in growth mode, and now they’re in contraction mode. So I think there will be some earnings headwinds.”
Changes in progress
On Friday, the bank announced that it had hired two experienced executives to oversee consumer and small business banking, a move intended to increase accountability in each of those segments, and that the former head of consumer and small business banking was leaving the company.
It also announced it would sell almost all of the assets of LightStream, the unsecured lending platform it acquired in 2012, to the Carlyle Group, marking the bank’s latest move away from non-core lending.
The LightStream deal, which includes $7.7 billion in non-core loans, is expected to be finalized by the end of the year. It will generate $7.2 billion in net proceeds, which
Lyon, the
Although he will have time to start shaping
“Virtually everyone I know has a very high opinion of Mike and what he will be able to do, but even though Mike is new, the story of
So far, the results have been mixed, according to Lyons. The branch network is strong and there are several high-quality businesses, such as corporate lending, commercial real estate and wealth management, he said. At the same time, “we found that capital was spread across many areas,” including areas that don’t support the bank’s core strategy, Lyons said.
“We have a clear vision. … Is it strategic? (Are there) clear financial returns? Or does it … do anything to protect the bank?” he said. “If it’s not, we’ll move it.”
The bank has already taken some steps to exit domestic businesses, as it attempts to focus on its core southeast market. In September he said it
In July, before Lyon’s arrival and shortly after setting higher profitability targets, the bank said it
As part of the leadership changes announced Friday,
In a post Friday on LinkedIn, Wilson said he had “deep optimism for
Meanwhile, D. Steve Boland, the former chief administrative officer of Bank of America, joins
Boland is set to join
Shimna Sameer, another longtime BofA executive, will become
Additionally, Jeff Warner will join the team later this month to serve as Director of Small Business Banking. Warner was named head of small business at Pittsburgh-based PNC in December 2024, according to his LinkedIn profile. His 17-year tenure at the PNC overlapped with that of Lyon.
Boland, Sameer and Warner will report directly to Lyon, the bank said.
Rogers remains with the bank, serving as executive chairman of the board. He plans to retire completely
Third quarter results
Excluding these items, net income was $1.4 billion for the quarter, the bank said.
Earnings per share were 56 cents, missing the consensus estimate of $1.21 from analysts surveyed by S&P Capital IQ. Total revenue was almost $3.8 billion, down from $5.2 billion in the corresponding quarter a year earlier, while non-interest expenses rose slightly to $3.1 billion as of September 30.
The bank’s net interest income increased by 0.7% year-on-year, mainly due to repricing of fixed assets and liabilities, higher customer deposit balances and higher loan balances.
Learn more:
Noninterest income fell 95% from the same period last year, reflecting the $1.4 billion securities loss as well as a decline in mortgage banking fees and “other income,” the bank said.
The bank’s return on tangible equity was 7.2% for the quarter, or 14.6% on an adjusted basis.
What Lyons does next and how he decides to shape
“Defining who they don’t want to be is sometimes as important as defining what they want to be,” he said.
Gn bussni