
Jeff Sica of Circle Squared Alternative Investments joins Stuart Varney to analyze how rising borrowing costs are crushing the real estate industry and how high food inflation is reducing profit margins for major restaurant chains.
Mortgage Rates hit its highest level since November 2023, mortgage buyer Freddie Mac said Thursday.
Freddie Mac’s latest primary mortgage market survey, released Thursday, showed the benchmark’s average rate. Fixed mortgage over 30 years rose to 7.28% from last week’s reading of 7.03%.
The average rate for a 30-year loan was 6.34% a year ago. Thursday’s figure is the highest since November 22, 2023, when the average rate for a 30-year fixed-rate mortgage was 7.29%.
MORE HOUSES, MORE PRICE BAYS – BUT BUYERS STILL AREN’T BITTING AS MORTGAGE RATES RISE

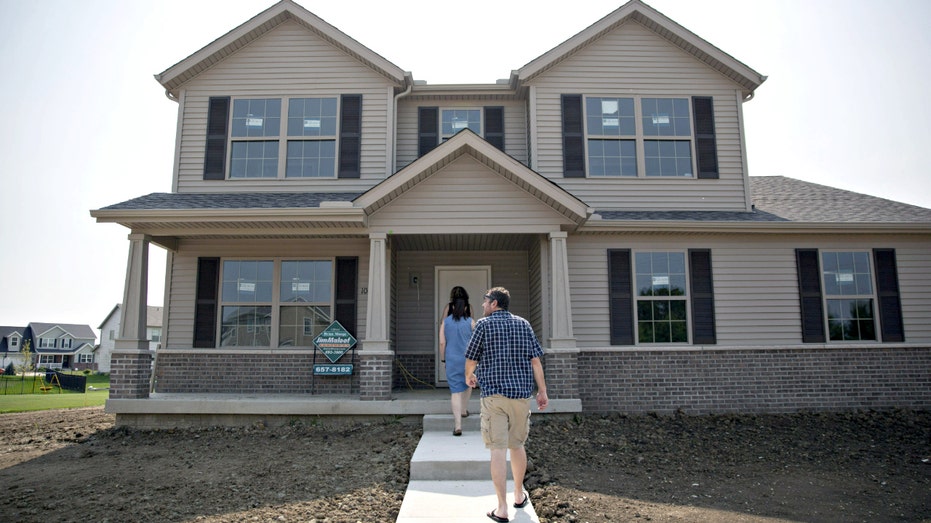
The 30-year fixed mortgage rate increased to 7.28% from 7.03% last week. (Daniel Acker/Bloomberg via Getty Images)
“With mortgage rates on their current trajectory, the housing market continues to be supported by favorable economic conditions,” said Sam Khater, Freddie Mac’s chief economist.
The average rate on a 15-year fixed mortgage rose to 6.6% from 6.42% last week.
RANKING AMERICA’S BEST AND WORST CITIES FOR HOUSING AFFORDABILITY
Mortgage rates are affected by several factors, including Federal Reserve and geopolitics. Although mortgage rates are not directly affected by the Fed’s interest rate decisions, they closely track the 10-year Treasury yield. The 10-year yield was hovering around 5.23% Thursday afternoon.
US CITIES WHERE HOME PRICES ARE FALLING FASTEST
“The 30-year mortgage rate has increased by almost a percentage point over the past year, significantly affecting buyers’ budgets,” said Hannah Jones, senior economist at Realtor.com. “This increase added more than $200 to the monthly principal and interest payment on a median-priced home, even though the median price fell year over year. In a volatile rate environment, the best thing buyers can do is rate-proof their budgets.”
GET FOX BUSINESS ON THE GO BY CLICKING HERE
Jones added that the overall rate is only part of the picture.
“Even in the same rate environment, most borrowers’ rates span nearly a full percentage point based on their credit score, down payment and lender choice, a difference worth about $28,400 in purchasing power,” she said. “Planning for both the market and their own financial profile can help buyers approach the purchase of a home with confidence.
Gn headline