
Netflix just beat its profits and still got punished, losing nearly half its value over the past year while its margins gradually widened. Something about these calculations doesn’t add up, and the answer determines where the stock goes from here.
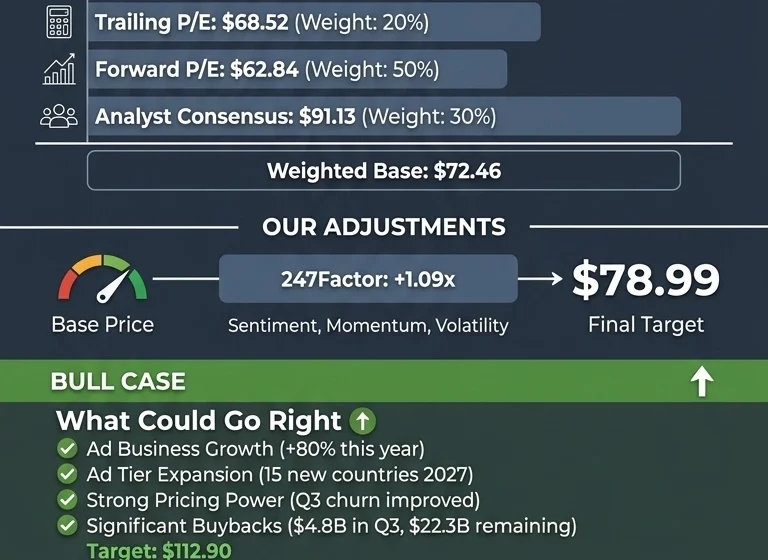
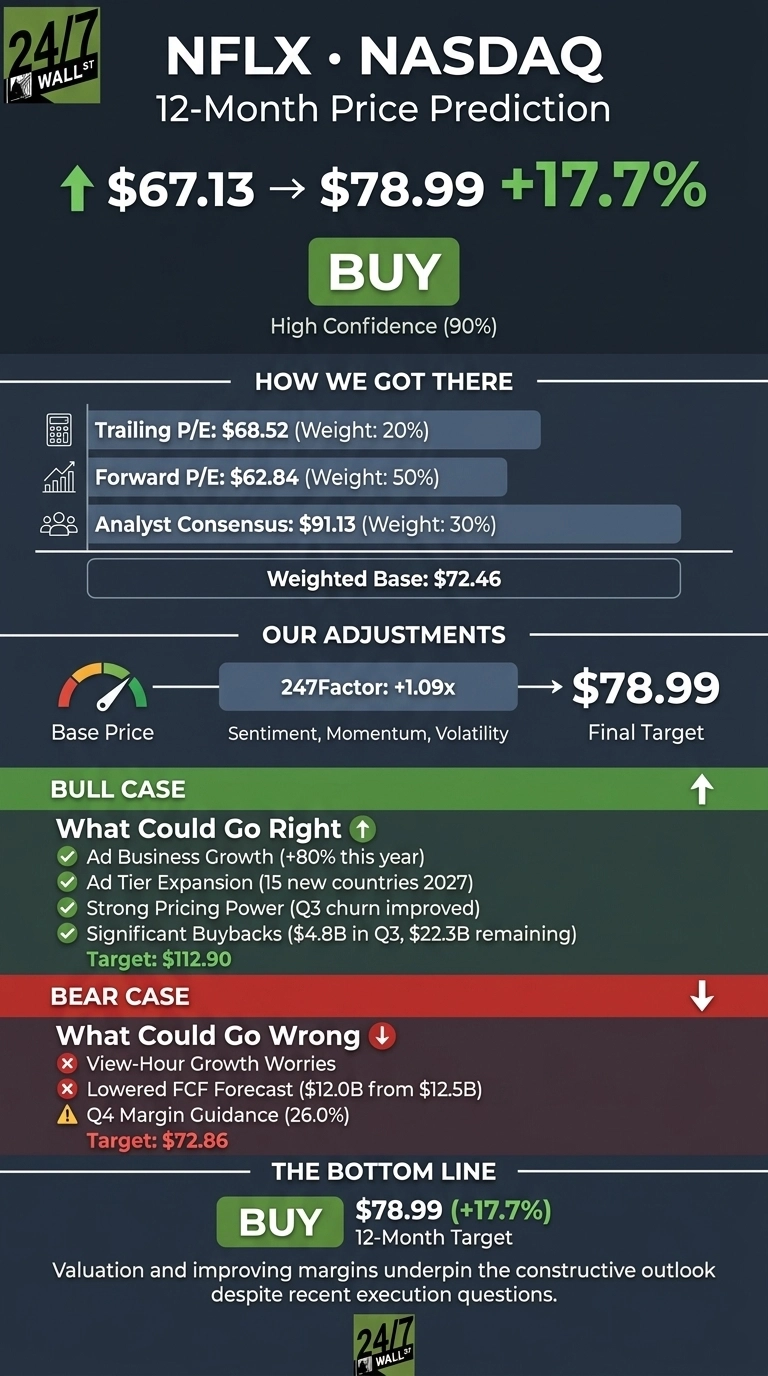
Our 24/7 Wall Street price target for Netflix (NASDAQ: NFLX | NFLX Price Prediction) is $78.99 over the next 12 months. Shares are trading at $67.13, so the target means a 17.7% upside. We view Netflix as a purchase with great confidence.
Wall Street 24/7 Price Target Summary
| Metric | Value |
|---|---|
| Current price | $67.13 |
| 24/7 Wall St price target. | $78.99 |
| Up/Down | 17.7% |
| Recommendation | BUY |
| Confidence level | 90% |
After a year of questions, the market evaluates Netflix as a franchise whose growth is running out of steam. What we see is a company that continues to grow revenue by double digits, expanding margins and buying back shares at a record pace.
Sentiment and fundamentals have moved apart, and this is why our model remains constructive even after a severe revision of expectations.
A 45.92% drop that ignored the increase in profits
Netflix is down 4.87% over the past week, 8.49% over the past month, 5.09% over the past quarter, and 28.4% year to date. The stock has lost 45.92% over one year. Shares are 42.5% below their 52-week high of $116.73 and just 4.7% above the low of $64.10.
The third quarter results as of October 20 show how much this gap has widened. EPS of $0.87 beat the estimate of $0.8229. Revenue of $12.874 billion (+11.85% YoY) was just below the consensus of $12.878 billion. The operating margin widened to 34.6% from 28.2%.
Despite this, shares fell 5.31% on results day. Netflix cut its 2026 ad revenue forecast from $3.00 billion to around $2.70 billion, and co-CEO Ted Sarandos admitted, “We need better execution in the US.” » Today, the stock is up 3.21%.
Why Bulls See $112.90 Ahead
The bull case reaches $112.90. Advertising is still early. Management said, “We continue to grow our advertising business by more than 80% this year” and advertising tiers will launch in 15 new countries starting in March 2027. Pricing power appears strong, with better-than-expected third-quarter churn both globally and in the U.S., while Latin America revenue grew 17%.
Netflix repurchased 63.9 million shares for $4.8 billion in the third quarter and has $22.3 billion remaining on its authorization. Analysts agree, with 7 strong buy and 28 buy ratings versus 15 hold and 1 sell.
Concerns over viewing hours could limit rebound
The bear case lands at $72.86. CFO Spence Neumann said: “We want to increase the number of viewing hours faster. We are not satisfied.” Netflix also lowered its FCF guidance for fiscal 2026 to around $12 billion from $12.5 billion and guided fourth-quarter operating margin to 26%.
The reduction in FCF comes from a one-time real estate transaction in the fourth quarter. The margin forecast takes into account approximately 120 basis points from job cuts, which should reduce costs over time.
Netflix earns its bounty on Disney and Spotify
Disney (NYSE: DIS) competes directly for streaming subscribers. It trades at 16 times earnings, but its operating margin is 14.6%, about half of Netflix’s 29.49%.
Spotify (NYSE: SPOT) runs the same subscription and advertising model. Its third-quarter revenue rose 16.32%, but it trades at 49 times earnings. Netflix falls in between with the best margins, making our 24/7 Wall Street price target look reasonable and arguably conservative.
| Business | P/E | P/FCF | Operating margin |
|---|---|---|---|
| Netflix | 25x | 29x | 29.49% |
| Disney | 16x | 19x | 14.6% |
| Spotify | 49x | 38x | 12.8% |
Valuation tilts our model towards Netflix near $67
My price target at Wall St. 24/7 is $78.99, rated Buy with a 90% confidence level. What tips the scales is the evaluation.
The stock has become cheaper while margins have widened. The case will strengthen if advertising resumes in 2027. It will weaken if U.S. viewing hours continue to stagnate. At these levels, our model sees more reward than risk.
| Year | 24/7 Wall St price target. |
|---|---|
| 2026 (December) | $68.80 |
| 2027 (October) | $78.99 |
| 2028 (October) | $87.70 |
| 2029 (October) | $97.58 |
| 2030 (October) | $101.57 |
The projections are based on Netflix continuing to implement its current strategy. Faster ad monetization could generate much higher results than these, and persistently low engagement could drag them down.
Contact (email protected) for any questions or corrections.
Gn bussni