Not Nvidia. Not Micron. If I could buy and hold just one artificial intelligence (AI) chip stock until 2030, it would be this one.

Every GPU that powers a model training cluster has to be built somewhere, and that somewhere is almost always a factory operated by Semiconductor manufacturing in Taiwan (TSM -0.72%). Taiwan Semi doesn’t design the artificial intelligence (AI) chips that make headlines. Instead, the company makes them on nodes that no one else can reach reliably and at scale.
This discrete competitive advantage has made TSMC the physical backbone of building AI infrastructure. However, the conversation always seems to start and end with Nvidia (NVDA +0.14%), Advanced microdevices (AMD +2.80%)Or Micron technology (UM -1.73%). The foundry that actually prints the silicon rarely gets the same airtime.
This gap is strange once you understand how the AI chip stack works. As designers continue to fight over architecture and software, the constraint that determines how many of these designs actually deliver is the capacity of advanced nodes – and TSMC owns most of that market.
Image source: Getty Images.
Foundry actually supports AI chip stack
Nvidia and AMD design GPUs while Micron creates memory solutions layered on top of these chips. However, none of these companies do all the manufacturing work to bring their products to life. TSMC has about 73% of the foundry market purely measured by revenue and would be closer to 90% of the market for the most advanced nodes.
For years, Apple has been recognized as TSMC’s largest customer. However, Nvidia regained this title earlier this year. This change directly follows the AI infrastructure cycle. High-performance computing, the field that covers AI accelerators and related server silicon, has become Taiwan Semi’s main growth engine.
The company’s management emphasizes that AI accelerator revenues will grow in the range of 50% through the end of the decade and has raised its outlook for the company’s long-term revenue growth to at least 25%.
While competition from Samsung and Intel exist, both companies are spending heavily to expand their foundry operations and neither company has yet closed the gap in yield and volume at the nodes that Nvidia and AMD actually need for current and next-generation accelerators.

Semiconductor manufacturing in Taiwan
Today’s change
(-0.72%) $-3.50
Current price
$482.30
Key Data Points
Daily scope
$481.48 -$486.00
52 week range
$266.82 -$487.47
Volume
8.3 million
Average flight
11.5 million
Gross margin
63.08%
Dividend yield
0.78%
Taiwan Semi’s growth is structural
TSMC’s financial growth supports the idea that the AI infrastructure supercycle is more than a temporary surge. Full-year 2025 revenue reached approximately $122 billion, up nearly 36% year-over-year. At the same time, the gross margin increased to 60%, compared to 56% the previous year. During the first half of 2026, Taiwan Semi’s revenue grew 37% year-over-year to $76.1 billion, while gross margin increased to around 60%, highlighting the level of pricing power the company currently has.
The company also spends a lot of money on capital expenditures (capex) to stay ahead of demand. Increasing infrastructure spending may seem expensive in a single year, but over the course of a multi-year AI development, it’s what keeps the enterprise gap intact. Customers cannot easily dual-source manufacturing for cutting-edge nodes. Taiwan Semi’s revenues and profits are therefore linked to the duration of the infrastructure supercycle itself rather than the launch of a specific product.
Taiwan Semi Stock May Be Ready for a Leak
The chart below illustrates how investors are treating TSMC as a pick-and-shovel name that should trade at a discount to some of the major chip designers. The current price-to-earnings (P/E) ratio puts the stock near 34 times, which looks rich at first glance. But on a forward P/E basis, Taiwan Semi is a different story. While the company’s forward P/E of 28 is not a significant value multiple on its own, it is also not competitive with a company that still expects revenue growth in the high double-digit percentage range and compound earnings as margins hold up.
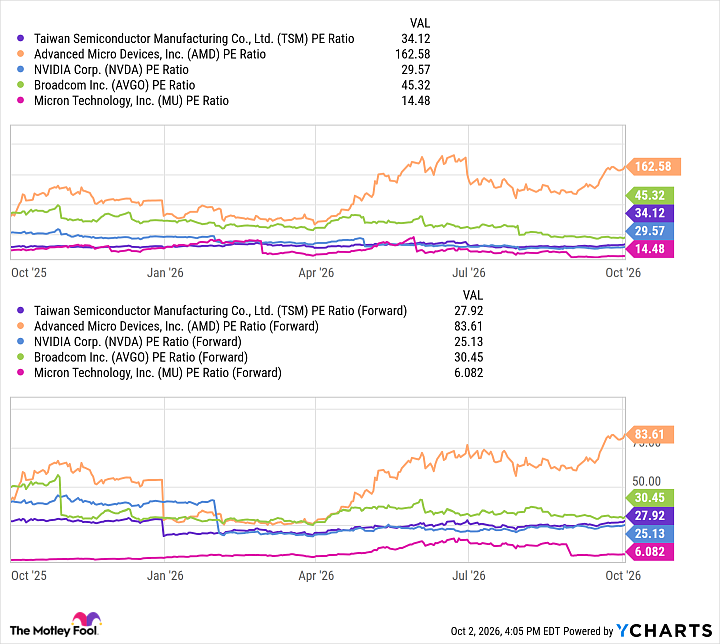
TSM PE ratio data by YCharts
Nvidia and AMD capture more of the narrative premium because their products are visible. For now, Micron will follow the cycle of increasing the memory that AI also needs. Taiwan Semi lies below each of them.
While geopolitical risk around Taiwan is an obvious factor to consider, aside from the cost of building manufacturing plants here in the United States, they do not erase the position of a foundry remaining the most difficult to replicate part of the AI supply chain. Based on the forward earnings assessment, I think TSMC stock still appears to be a strong buy-and-hold candidate throughout the AI infrastructure era.
Gn bussni