Micron (UM -7.00%) the stock had an excellent year in 2026. It is the fourth best performing stock S&P500 stock this year, up about 220% so far. In many years, that might have been enough to make it the top performing stock, but with so many big winners this year, it’s going to have to settle for a top five finish.
I could see him repeat this performance in 2027. How? It simply needs to execute its business and trade at a reasonable valuation.
Image source: The Motley Fool.
Demand for memory chips is huge
Micron makes memory chips. There are two main types: DRAM and NAND. NAND is what is used for long-term data storage, such as in Solid State Drives (SSDs). DRAM is faster, but cannot retain information when the chip is not powered. These are used in consumer computers and AI computing units. AI computing units use a specific sub-segment of DRAM, called high-bandwidth memory (HBM). While all types of memory are rare, it is HBM that is really the focus.
There is not enough memory chip production capacity worldwide to meet growing demand, so the industry is in a supply-constrained situation. Even though all major players in the memory industry are building new manufacturing facilities, the situation is not going to improve anytime soon. Micron told investors during its latest earnings conference call that it expects stress in the memory market to worsen in 2027 and 2028.
Micron itself plans to open six new production facilities (three by mid-2027 and three in 2028) over the next two years. This will significantly increase its production, but it remains to be seen whether this increase, along with the additional capacity of its peers, will be enough to satisfy demand from AI data center operators.
UM Micron technology
$795.23-$59.87 (-7.00%)
NASDAQ · At 4 p.m. ET on 04/11/26
Furthermore, one of Micron’s two main competitors, SK Hynix, recently said it has pre-sold all the HBM and DRAM it will have the capacity to manufacture through 2029. Micron is likely experiencing similar demand, and with capacity sold three years in advance, it is likely that 2030 and 2031 will also see shortages.
These conditions will keep memory chip prices at sky-high levels for many years, which bodes well for Micron’s business. The memory industry has a history of cyclical downturns, but the next one may not arrive for five years or more. This gives it enough time to make a lot of money and buy back huge amounts of stock to increase shareholder returns.
After all, its stock is very cheap.
The market does not highly value Micron shares
Micron’s stock is valued cheaply, trading at just 12 times current earnings and 5 times forward earnings.
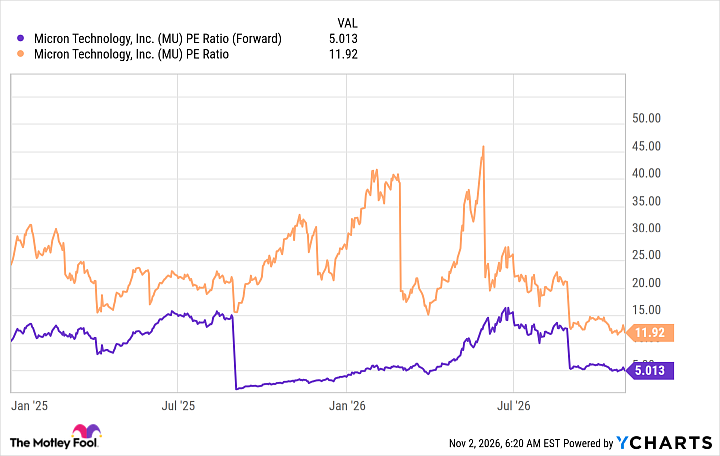
MU PE ratio data (front) by YCharts.
Over the past few years, Micron shares have traded at more than 20 times current earnings. If the company meets analyst expectations and its shares return to this level, they will quadruple. While I think it’s highly likely that the market is truly underestimating Micron’s growth drivers, I’m not sure the stock will be fairly valued.
The market currently has a bearish view on AI due to the scale of capex it happens in space. However, I think this is short-sighted, and the scale of growth in the AI sector justifies the spending. All AI hyperscalers have told investors that they view the risk of underspending and delay as much worse than the risk of overspending on infrastructure. Additionally, this market is still in a complex and contested state at present, so overspending on AI computing capacity is really not a concern, at least for now.
Micron will continue to play an important role in the development of AI infrastructure and right now seems like a great time to buy shares.
Gn bussni