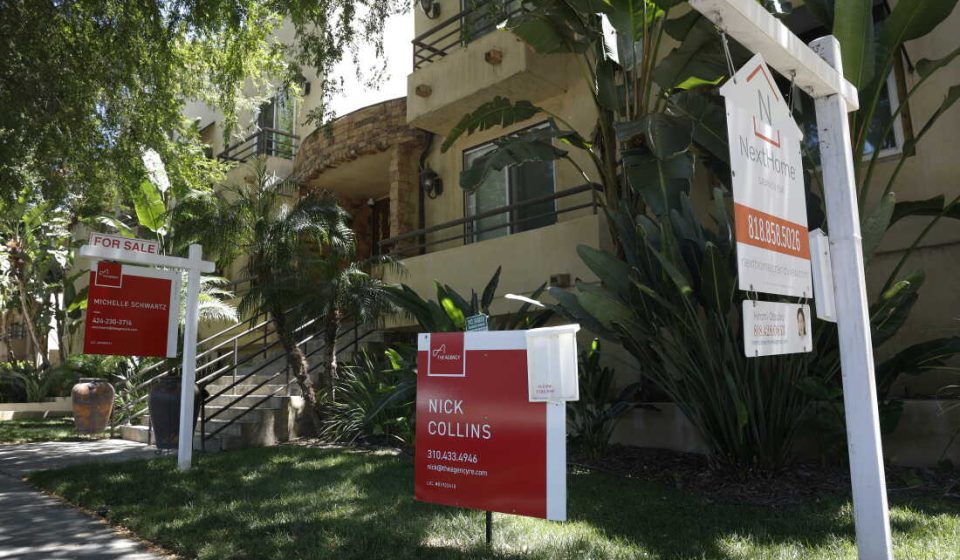


For sale signs are posted in front of condominiums for sale in July in Los Angeles. A new analysis from the Center for Responsible Lending finds that the average renting household now needs 16 years to save for a down payment and closing costs.
Justin Sullivan/Getty Images
hide caption
Justin Sullivan/Getty Images
Mortgage rates above 7% are the latest sign of how difficult it is to buy a first home, with would-be homeowners already facing exorbitant prices. A new analysis released Thursday highlights another growing barrier: the amount needed to close a home loan.
“Over the past seven years, the time it takes to save down payment and closing costs has doubled,” said Mike Calhoun, president of the Center for Responsible Lending, a nonprofit research organization that promotes economic opportunity. The report was published by the center’s Julian Bond Institute.
Since 2019, the last time the center made the same calculation, real estate prices have soared, inflation has soared and remained stubbornly high, and the rising cost of food, gasoline, health care and more has strained family budgets. Home loan closing costs have also increased, in part due to the rise in home insurance.
Amid all this, renters’ incomes have not kept pace and personal savings rates have plummeted.
Today, the center calculates that for a median-income renting household, it would take “a staggering 16 years” to save the down payment and closing costs on a first home. That’s twice as long as it was in 2019. And it would take even longer – 21 years – for a Black renting household at median income.
This kind of delay upends one of the main reasons many are looking to buy in the first place. As the analysis notes, “by the time the family begins saving, young children may have left the household – to pursue higher education or work – before the family has saved enough to purchase its first home.”
The report also limits its calculations to middle-income households — earning between $50,000 and $120,000 — whose members are more likely to be viable homeowners. For them, the time saved also doubled to 12 years.
For front-line workers, such as police officers, firefighters, EMTs, nurses and teachers, researchers find that “the years to save have at least doubled and are now between 10 and 13 years.”
As grim as those numbers are, Calhoun said they are likely an underestimate.
The center’s calculations call for a 3.5 percent down payment, since that’s what the Federal Housing Administration requires for first-time buyers. The median first-time buyer actually pays around 10%. The report also assumes that families are “actually maximizing their savings,” he said, even though many can’t save at all, are forced to eat through their savings or go into debt.
The gap in the housing economy has widened
The report from the Center for Responsible Lending highlights a stark divide in the housing economy, exacerbated when the COVID-19 pandemic triggered a spike in inflation, mortgage rates and home prices.
“If you look at the last seven years, they’ve been extraordinarily good for owners,” Calhoun said. Those who bought when prices were much lower accumulated huge amounts of equity as home values soared. Some were also able to reduce their monthly payments through refinancing, as mortgage rates hit historic lows of around 2% or 3% before climbing.
Many homeowners with low interest rates have decided they can’t afford to move and have seen their mortgage payments double. That means fewer seniors have downsized and fewer people put their homes on the market, intensifying the national housing shortage.

At the same time, rising rents have absorbed a growing share of family income, according to a recent report from the Harvard Joint Center for Housing Studies. “From 2001 to 2024, tenant incomes increased by 9 percent in real terms while rents increased by 30 percent,” the report said. This forced a quarter of tenants to pay more than half of their income in rent and utilities.
Despite a recent slowdown in rental markets, a record number of tenants are still considered cost-burdened. Low-income households are also hit harder by inflation, as basic goods and services make up a larger share of their budget.
The center calculates a starting cost for a home of $335,574, or 80% of the median sales price of existing homes. And the center finds that it takes less time to save a down payment and closing costs in some large metropolitan areas than in others — from 11 years in Houston to 24 years in Los Angeles.
The report also notes that housing costs have outpaced incomes almost everywhere and that “the problem is even more acute in the fastest-growing rural areas than in urban areas.” A recent analysis by center-left think tank Third Way found that housebuilding has failed to keep pace with rural growth, creating severe pressure on affordability.
Many buyers rely on help from family
The growing housing wealth gap leaves a more privileged share of Americans able to purchase a home. “Cash purchases are up sharply,” Calhoun said. For younger buyers, “the main way to find money is through help from family, the ‘mommy and daddy bank’ and friends.”
Far fewer buyers benefit from down payment assistance programs, even though there are thousands of them. “Programs are often short of money,” Calhoun said. “A lot of them are very small and idiosyncratic.”
He’d like to see more aid programs “to reach a broader range of people who don’t have intergenerational wealth.”

The center’s report also calls for zoning and other reforms to boost the supply of smaller, cheaper starter housing, including duplexes, townhouses and manufactured housing. A sweeping new law passed by Congress this year aims to promote that, but it’s up to states and cities to follow through, and creating a new offering will take time.
Despite all that, a related survey from the center finds that millennials and Generation Z are aspirational toward homeownership at the same rate as previous generations — a “testament to the resilience of the American dream,” according to Thursday’s report.
It’s the primary way “most families generate wealth that they can pass on to the next generation,” said David Silberman, co-author of the report. “I think the case for homeownership remains very strong, despite all the trends we’re reporting in the challenges to getting there.”
Gn bussni