
Tesla will report its third quarter 2026 financial results tomorrow, October 21, after the market close. The earnings call follows at 5:30 p.m. ET.
Wall Street expects revenue to remain flat and earnings per share to fall 10% from last year, even though Tesla just beat its own consensus to deliver more than 24,000 vehicles.
Tesla deliveries and energy deployment in the third quarter of 2026
We already have the volume numbers. Tesla delivered 486,532 vehicles in the third quarter, down 2.1% from its all-time high of 497,099 in the third quarter of 2025, but well above the Tesla consensus 461,974 set by 24 analysts.
It only built 464,391 vehicles during the quarter. As a result, Tesla delivered 22,141 more cars than it produced, and for the second quarter in a row it reduced its inventory after building about 50,000 excess vehicles in the first quarter.
It’s still a two-car business. Models 3 and Y accounted for 478,237 of those deliveries, while “other models” (Cybertruck, Semi, and what’s left of the Models S and X) fell 48% year over year to 8,295 units.
Energy storage was the weak point. Tesla deployed 13.7 GWh, up 9.6% from 12.5 GWh a year ago, but well below the roughly 15.9 GWh expected by analysts and below the record of 14.2 GWh set in the fourth quarter of 2025.
Tesla revenue for the third quarter of 2026
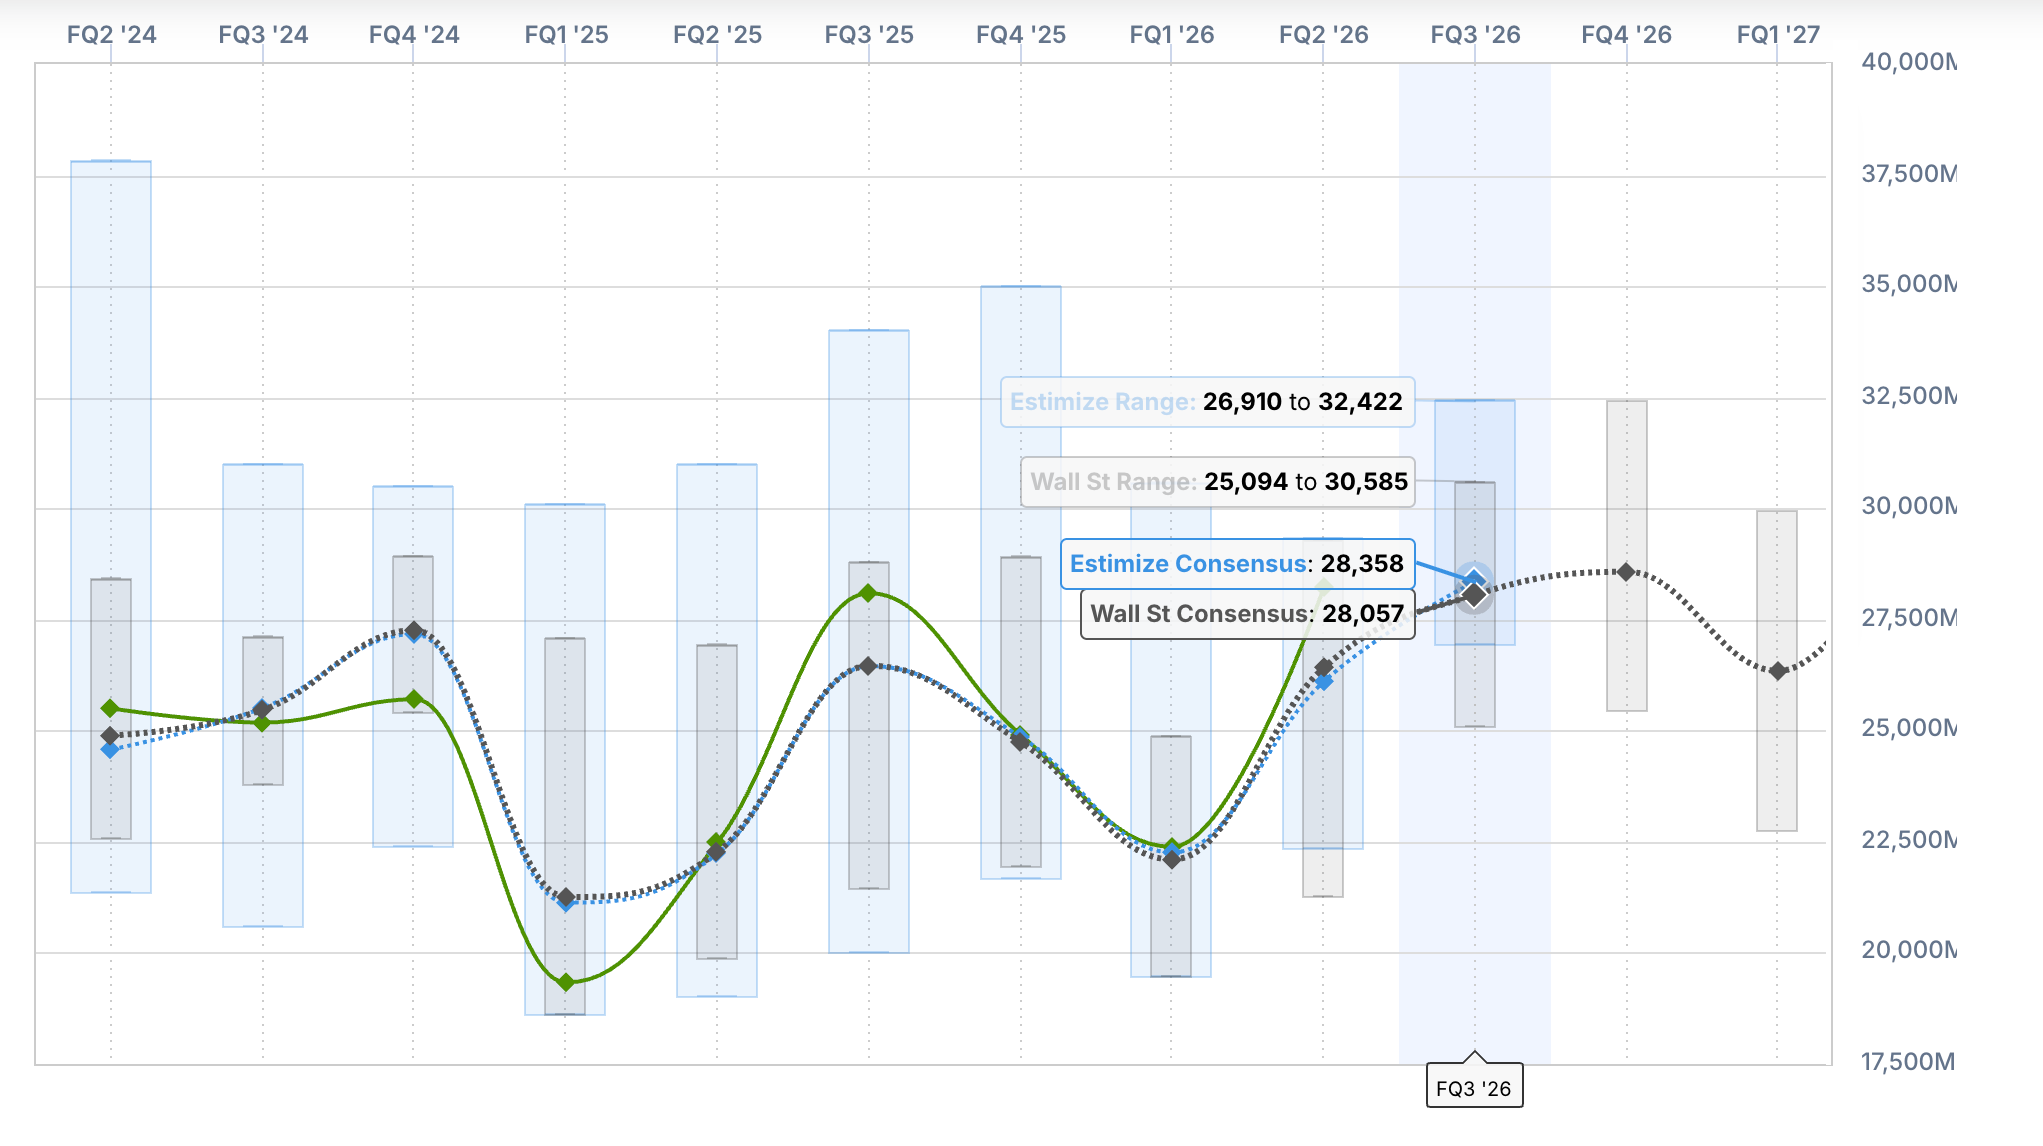
The Wall Street consensus calls for revenue of $28.06 billion, while the estimate is a bit more optimistic at $28.36 billion. Regardless, that’s still stable compared to the $28.1 billion Tesla reported in Q3 2025. Wall Street estimates range from $25.1 billion to $30.6 billion.
The apartment is not as bad as it seems. The third quarter of 2025 was inflated by U.S. buyers rushing to grab the $7,500 federal tax credit before it expired on September 30, 2025, so matching it without the credit would be a decent result.
But look at the sequential image. Tesla reported revenue of $28.24 billion in the second quarter of 2026 on 480,126 deliveries and 13.5 GWh of storage. The third quarter saw more of both, but Wall Street is modeling slightly lower revenue and estimating only about $120 million more, meaning both are bracing for lower average sales prices.
Tesla third quarter 2026 results
Analysts expect non-GAAP earnings per share of $0.45, down 10% from $0.50 in the third quarter of 2025. The Estimize consensus is a bit higher at $0.48, and Wall Street estimates range from $0.30 to $0.70.
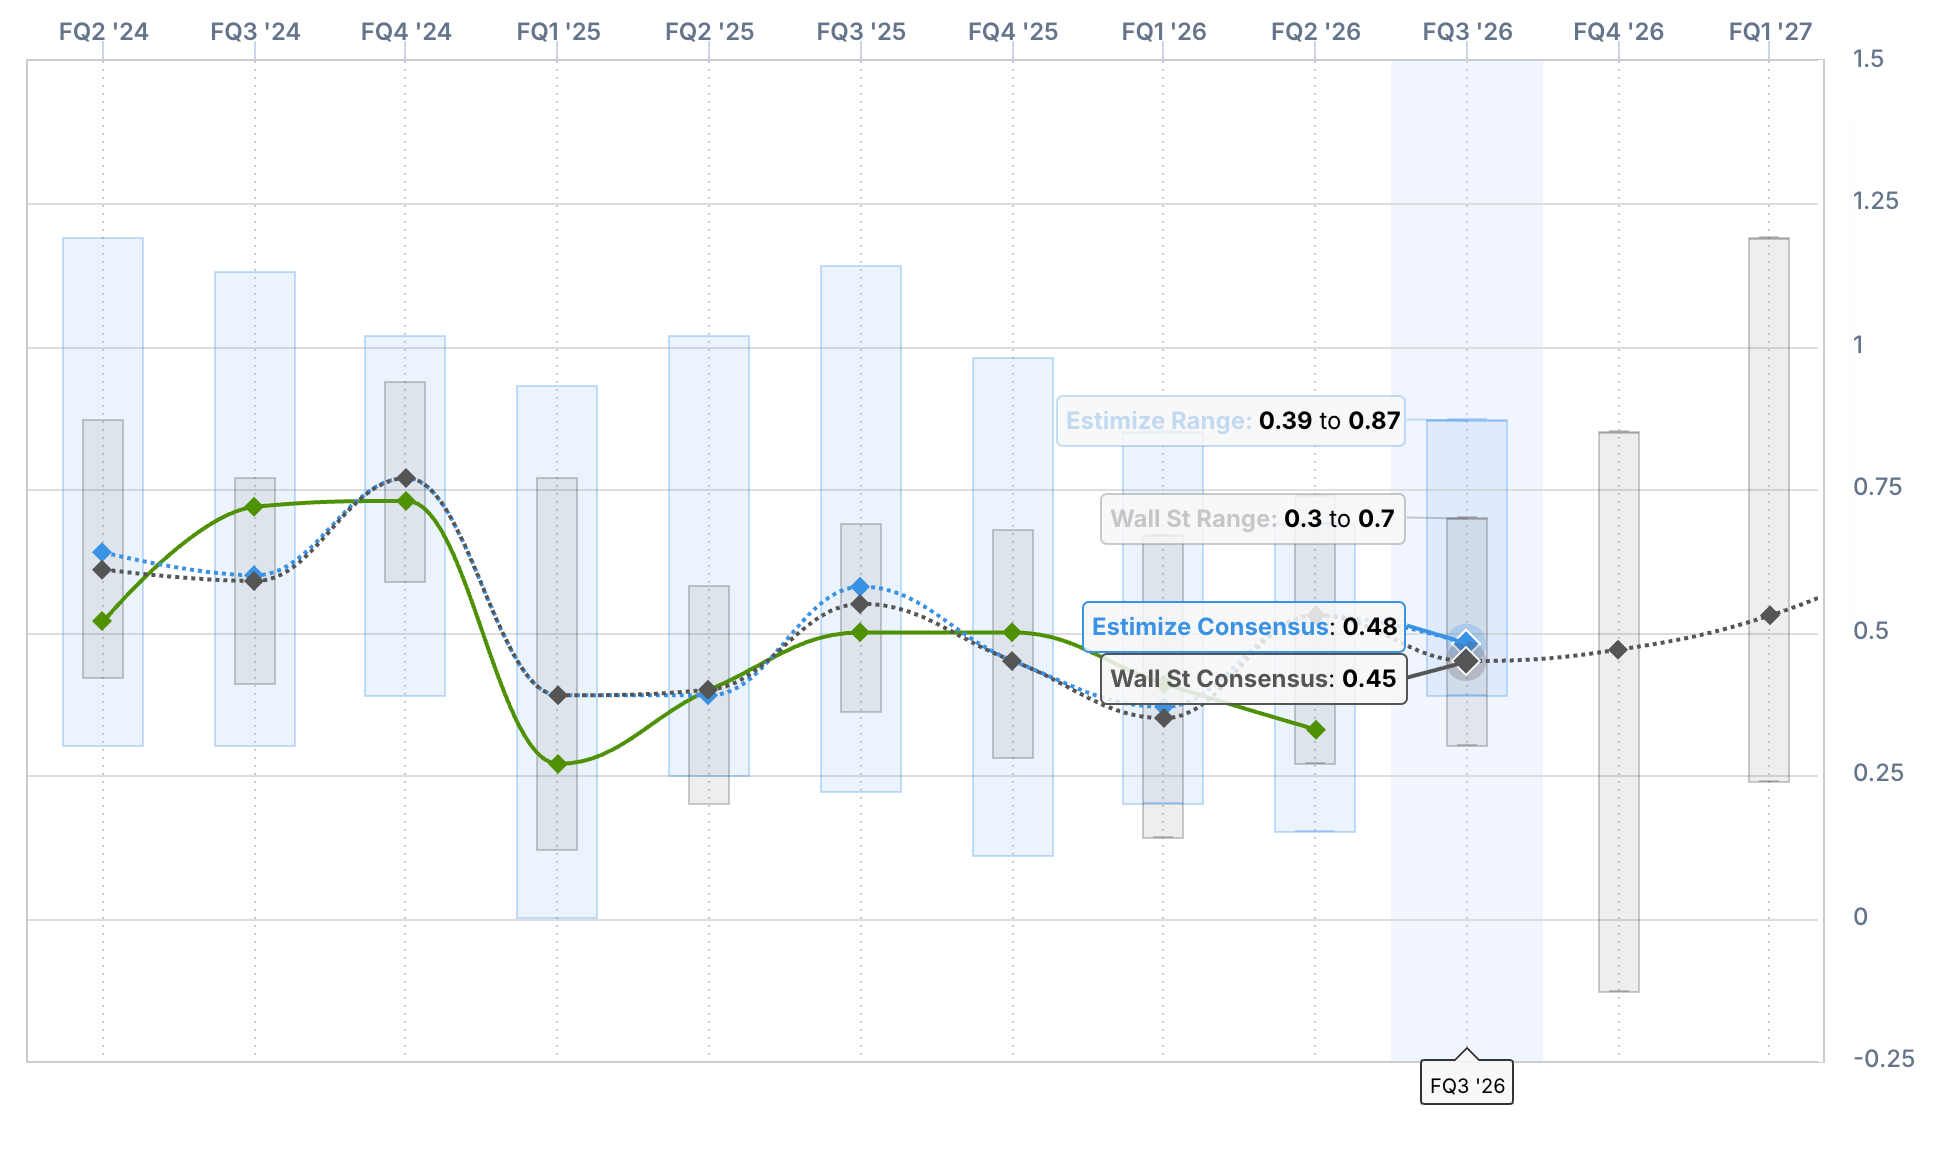
Take this number with a grain of salt. In the second quarter, Tesla came in at $0.33 versus a consensus of $0.53, with its operating margin collapsing to 1.4%. Operating profit fell 57% to $398 million while operating expenses jumped 47% to $4.35 billion.
Tesla has now missed the Street’s EPS estimate in two of the last four quarters. And its EPS has declined year over year in five of the last seven years.
The number we will watch first is the automotive gross margin excluding regulatory credits. It fell to 16.3% in the second quarter from 19.2% in the first quarter, which Tesla blamed on a $230 million warranty reduction and tariff relief that helped the first quarter and was not repeated.
Regulatory credits won’t save it either. They brought in just $146 million in the second quarter, down 67% from the previous year, and those purely lucrative revenues continue to decline now that automakers no longer face federal CAFE penalties.
Then there’s the money. Tesla burned through $1.09 billion in free cash flow in the second quarter, with capital spending more than doubling to $5.8 billion, and management pointing toward more than $25 billion in investments for 2026, with spending weighted to the second half. Another quarter of negative free cash flow wouldn’t be a surprise.
The energy is also worth seeing. The storage business had a gross margin of 20.4% in the second quarter, and Tesla says it expects a low-to-mid margin of 20% over the long term. With Q3 deployments missing estimates by more than 2 GWh, energy won’t make up for much.
Top Voted Questions by Tesla Shareholders for Q3 2026
Tesla’s Q&A on Say Technologies for the call ends today at 4 p.m. ET. It attracted 832 questions from around 2,860 participants representing 3.85 million shares.
That’s more people than last quarter (around 1,710) but less than half the shares, which were 8.6 million in the second quarter.
Here are the main questions classified by actions represented:
- “How is the Cybercab fleet evolving beyond Austin and what is the regulatory path outside of Texas given NHTSA’s open safety review?” (980 votes, 1.2 million shares)
- “When can we anticipate unattended FSDs in customer cars? (1,200 votes, 1.1 million shares)
- “When will CyberCab be available for customer purchase/ownership?” (1,100 votes, 952,900 shares)
- “What is the unit profitability per mile of paid robotaxi, and how does it compare to the target of thirty cents? » (435 votes, 694,900 shares)
- When HW3 owners will know if they get a free hardware upgrade for unsupervised FSD (557 votes, 652,900 shares)
- “What is the Optimus cost per unit and what does the first paying customer look like?” » (699 votes, 643,600 shares)
Electrek’s point of view
The automotive sector is stagnant. Deliveries are up 8.8% year-to-date to 1,324,681, representing a real recovery after two years of decline, but the third quarter was lower than last year and Tesla is still selling almost nothing outside of the Model 3 and Model Y.
So the quarter comes down to margins and expenses. If automotive margins excluding credits remain around 16% and operating expenses stop rising by more than 40% per year, the failure of the second quarter was one-off. Otherwise, Tesla is spending more than $25 billion this year on AI, Optimus, Cybercab and chips, while its core business is barely breaking even operationally. This is an automaker financing a very expensive gamble with a shrinking profit pool.
And shareholders mostly don’t care. Look at the questions: Cybercab, FSD, Optimus, HW3. The main question regarding Tesla’s consumer lineup was a demand for a minivan.
They are completely delusional, waiting for dubious new products to make them money while watching their cash cows stop growing, which would have been entirely avoidable if Musk hadn’t bet too early on the autonomy of the entire company.
If you pay attention to the cost of ownership of electric vehicles, home solar is how you get near-zero fuel. With electricity rates up nearly 10% in the last year and expected to continue to rise, turning to solar power is one of the best ways to protect against rising costs. And with leasing and PPA options, you can do it without any upfront costs and start saving immediately. If you want to find the best deal, check out EnergySage. It’s a free service with hundreds of pre-screened installers competing for your business, so you save 20-30% compared to a stand-alone solution. No sales calls until you choose an installer. Get your free quotes here.
FTC: We use automatic, revenue-generating affiliate links. More.
Gn bussni