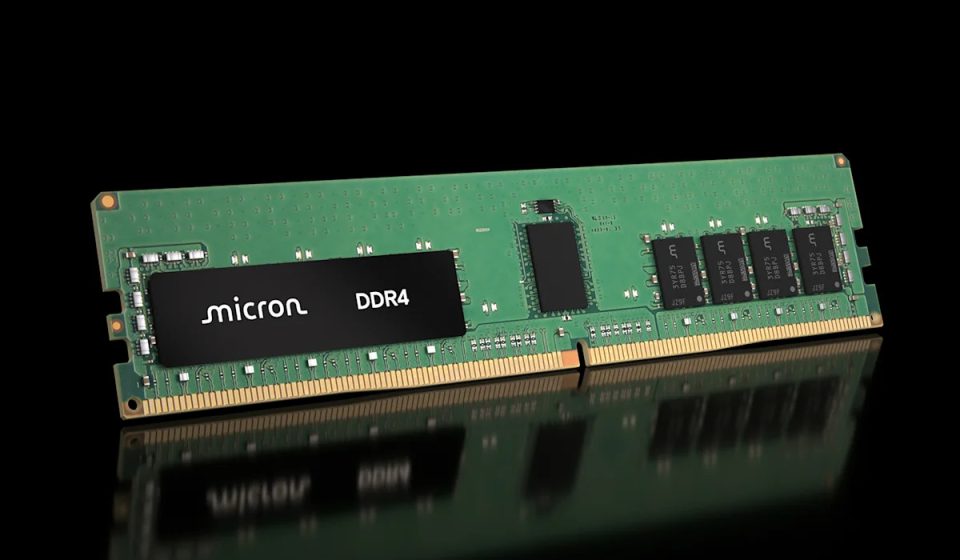
The biggest micron bull on Wall Street has just raised its target again. The stock now sees almost triple

Micron Technology Inc. (NASDAQ: MU) trades at about 6 times forward earnings, the kind multiple investors are offering memory makers that they expect to soon reach their peak. DA Davidson analyst Gil Luria thinks that’s a mistake. On October 7, he raised his price target from $2,100 to $3,000, which was already a high, and maintained a buy rating. Its target uses 19 times fiscal 2027 earnings, or about $158 per share, slightly below consensus. So almost all of the benefits come from investors paying a higher multiple. The stock is already up 260% this year. Micron’s rally hasn’t stopped it from making our list of undervalued stocks. See what other stocks offer potential value in October.

Management’s own comments support it
The reason I find Luria’s view compelling is how closely it aligns with Micron’s September 30 earnings announcement. CEO Sanjay Mehrotra said the company has signed 26 long-term customer agreements, covering more than 35% of its revenue through 2030. The agreements include approximately $150 billion in remaining performance obligations, as well as $32 billion in customer financial commitments, primarily made up of cash deposits. CFO Mark Murphy added that even at minimum contract prices, Micron expects margins well above any past highs. Mehrotra also said the company could not yet predict when supply would catch up with demand. Its long-term deals could provide more support for its earnings than in previous cycles. But is the market still treating it like a traditional memory stock? Find out why Jim Cramer thinks this stock may no longer be the same cyclical bet.
Micron’s investment plans are a risk to watch
Micron is spending heavily to keep up. It projects about $25 billion in capital spending in the first half of fiscal 2027 alone, and even more in the second half. Stocks fell in the hours following the report’s release as investors weighed those plans.
Analysts also appear cautious. They expect EPS to climb 133% in fiscal 2027 and 17% in 2028, but then fall about 32% by 2030. The forward non-GAAP P/E of 6.18x is well below its 5-year average of 74.26x, while the forward price-to-sales ratio of 4.29x is close from its norm of 4.17x. Such low multiples during record revenue quarters show that the market is still treating Micron like a typical cyclical memory company. With approximately $68.3 billion more in cash and marketable investments than debt, Micron has considerable financial flexibility to finance its construction.
Hedge funds have already joined in. Funds holding Micron increased from 154 in the first quarter to 184 in the second quarter. The value of their holdings more than doubled, from $14.3 billion to $34.9 billion.
Gn bussni