
By Jamie McGeever
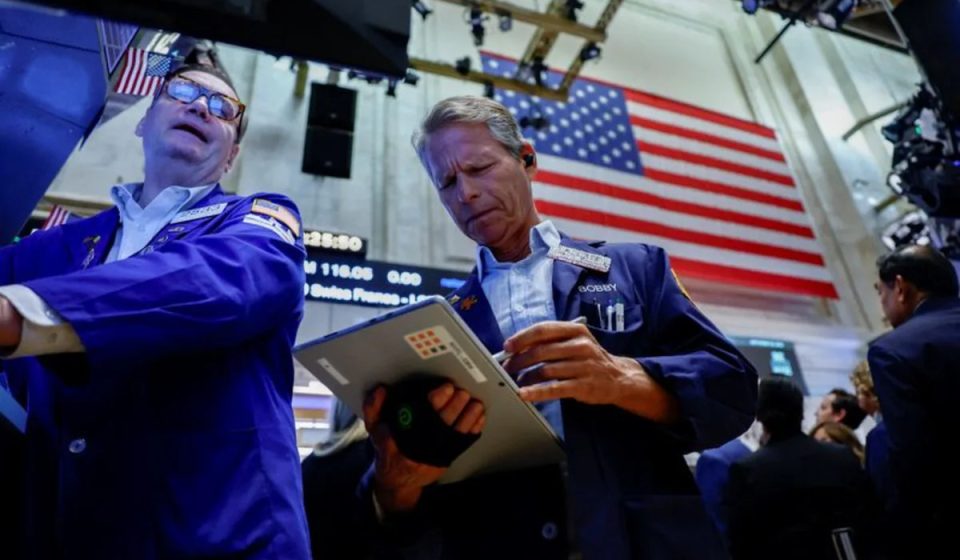
ORLANDO, Fla., Oct 15 (Reuters) – The rout in AI stocks accelerated sharply in Asia on Thursday amid growing fears about the shadowy and circular financing fueling the build-out of the intelligence revolution, even as its strength evaporated during trading hours in Europe and the United States. Still, safe-haven inflows helped U.S. Treasuries have one of their best days in months, despite a surprisingly sharp rise in U.S. producer inflation.
Key readings of the day
• CoreWeave crisis highlights growing debt burden behind AI boom
• AI credit concerns send insurance defaults to record high
• AI investment boom could mask US economic cracks: Mike Dolan
• Producer prices in the United States show the strongest increase in 4 and a half years; expensive gasoline boosts retail sales
• Warsh’s quest for a quiet Fed sparks backlash
• The main market movements today EQUITIES: Asia in the red, South Korea -7.5% at 6-month low, Japan -5%. UK +1% to 7-week high. Nasdaq +0.1%, S&P 500 +0.3%, Dow +1%. SECTORS/SHARES: Eight sectors up in the S&P 500, three down. Tech -0.5%, energy -1.5%, health +2%. CoreWeave +6.5%, Nike +5%. Hewlett Packard, Dell -7%.FX: The dollar slides, the biggest drop in six weeks. The biggest winner is the Swiss franc, +1%; The biggest drop is the Brazilian real, -1.5%. BONDS: Bund yield -11 basis points to 3.35%, the lowest in more than a month. US 10-year yield -10bp at 5.08%, flattened curve. CoreWeave and other AI company bonds are increasing. COMMODITIES/METALS: Mixed oil — Brent stable, WTI + 3%. Gold +1%, silver +3%.
Today’s talking points:
Funny money
The global AI business has seen major turbulence. South Korea’s KOSPI, one of the world’s top 10 indexes, lost 20% of its value in just a week, and on Thursday Japan’s Nikkei slipped 5%. CoreWeave 2032 bonds issued just four months ago have fallen below 80 cents on the dollar, which is generally considered a level of distressed debt, and the cost of insuring major U.S. AI companies against default has soared to record levels.
As always, credit markets are likely to dominate stocks, and the risk of a self-fulfilling doom loop cannot be ignored: selling of some securities casts a shadow over healthier credits, and downgrades and loss of investment grade ratings could force further selling. Meanwhile, cash has been spent and investments are increasingly financed by debt, private credit and off-balance sheet borrowing. We haven’t reached crisis point yet – look at the rebound in US stocks and bonds today – but vigilance is required.
Bonds be bonds
Available data shows that U.S. producer price inflation is higher than expected, like CPI the day before, WTI crude rises another 3% and Treasuries rebound. This seems counterintuitive, especially given the amount of trading in bond markets in recent weeks, but it shows that the disappearance of Treasuries’ safe-haven appeal has been greatly exaggerated.
Gn bussni