Skip to content
-
Subscribe to our newsletter & never miss our best posts. Subscribe Now!
Today's News. Tomorrow's Perspective. Today's News. Tomorrow's Perspective.

Deliver fast, factual, and easy-to-understand news covering global events, technology, business, science, AI, health, entertainment, and lifestyle.

Today's News. Tomorrow's Perspective. Today's News. Tomorrow's Perspective.

Deliver fast, factual, and easy-to-understand news covering global events, technology, business, science, AI, health, entertainment, and lifestyle.

  • Home
  • Breaking News
  • Business
  • Sports
  • Health
  • Politics
  • Technology & AI
  • World
  • Home
  • Breaking News
  • Business
  • Sports
  • Health
  • Politics
  • Technology & AI
  • World
Close

Search

  • https://www.facebook.com/
  • https://twitter.com/
  • https://t.me/
  • https://www.instagram.com/
  • https://youtube.com/
Subscribe
Wall Street sees ominous sign in latest bond market sell-off
Breaking NewsFeatured

Wall Street sees ominous sign in latest bond market sell-off

By adminvoxa
October 9, 2026 5 Min Read
Comments Off on Wall Street sees ominous sign in latest bond market sell-off

(Bloomberg) — It’s one of the least understood signals in the fixed-income world, but lately everyone on Wall Street is abuzz about what it means as it reasserts itself in the market.

Most read on Bloomberg

This is called the term premium, or the additional payment that investors demand in exchange for the risks of owning 10-year Treasury bonds instead of simply rolling over short-term securities for the same duration. The exact way to measure it varies. The same goes for the explanations of his movements.

What is beyond doubt is that in recent weeks it has surged to levels not seen in more than a decade and driven the latest wave of bond selling that has sent U.S. Treasury yields to a 24-year high. And that, in turn, is stoking fears of a potential shift that would increase pressure on an already battered market and keep borrowing costs high across the economy.

This term premium is essentially a hedge against unpredictable twists and turns, ranging from geopolitical shocks to government budget crises, that could hit the market before long-term bonds mature.

This is distinct from the current inflation outlook and monetary policy stance, both of which are also reflected in yields. Because the bounty is not directly observable and must be inferred, Neel Kashkari, president of the Federal Reserve Bank of Minneapolis, once compared it to dark matter, the invisible substance that physicists believe explains some cosmic mysteries.

“There are several ways to calculate it, but they all point upwards,” said Frank Rybinski, head of macro strategy at Aegon Asset Management. “And what that tells me is that this decision has endured.”

What Bloomberg strategists say…

“The sharp revaluation of the term premium embedded in Treasuries – with the 10-year term premium reaching a 12-year high – suggests that investors are demanding greater compensation for holding time amid increasing fiscal and geopolitical uncertainty.”

— Frank Monkam, macro market strategist

Click here to learn more

There was no clear catalyst. Barclays researchers led by Demi Hu said macroeconomic uncertainty, breaks in the usual correlations between stock and bond movements, the growing supply of debt and concerns about fiscal policy are all factors that factor into the term premium and could play a role.

Neil Shearing, chief economist at Capital Economics, said the recent move could reflect technical factors, such as portfolio adjustments late last month, or the side effects of growing concern in Europe over France’s debt levels. Stephen Douglass, chief economist at NISA Investment Advisors, pointed to some signs of stress in credit markets, as well as broader doubts among investors about the benefits of holding fixed-income assets when inflationary shocks become more frequent.

“It’s not a simple story,” said Douglass, who cautioned against reading too much into short-term movements. “But I would say I think we are in an environment of rising maturity premiums.”

This is a concern for bond bulls. A structurally higher term premium could keep long-term interest rates high, preventing the market from rebounding from its crisis.

This indicator fell steadily in the 1990s, when increasing globalization exerted a deflationary force, and fell further during the 2010s, as central banks’ quantitative easing programs distorted global bond markets by flooding them with liquidity. It fell as low as -1.7% in March 2020, when investors were rushing to the safety of bonds, before systematically climbing back into positive territory after the end of 2024, according to a model created by economists working for the New York Fed.

It remained relatively stable through most of the sell-off that began after the United States launched its war against Iran in late February.

Then, in mid-September, it started to skyrocket. The New York Fed’s model shows it climbed about 40 basis points to around 0.98%, the highest since 2014 and more than enough to explain the nearly 30 basis point rise in 10-year Treasury yields during that period. The Bloomberg Economics estimate shows a similar increase. Another, which factors in economists’ forecasts for Fed policy, rose to 1.08%, its highest level since 2010.

This upward breakout occurred while other price factors changed little. Inflation expectations remained stable. The Fed’s unanimous decision to raise rates last month eased some concerns about its desire to control consumer prices. And oil, although elevated to over $100 a barrel, remains within a tight range.

A sustained increase in maturity premiums would add to pressure on the market from high inflation, robust economic growth, as well as a flood of borrowing from companies investing in artificial intelligence and from deficit-making governments around the world. Dallas Fed Bank President Lorie Logan said last week that higher term premiums, by raising borrowing costs, could slow the economy and reduce the need for the central bank to raise rates.

“The bond market is no longer waiting for the Fed to tighten financial conditions,” said Florian Ielpo, head of macro at Lombard Odier Investment Managers. “Long-term premiums, inflationary uncertainty and government borrowing needs can keep long-term yields restrictive, even when the expected movement in short-term rates becomes less aggressive.”

One of the reasons for these latest measures could be the fallout from the disorderly selling of French bonds. Some also point to the hedging activity of holders of mortgage-backed securities that can temporarily exaggerate market movements.

Yet behind this may lie longer-term risks that have been building up in the global economy. The first is that shocks to the supply of energy and other raw materials – such as those following Russia’s invasion of Ukraine and the US war against Iran – could become more frequent as geopolitical divisions widen.

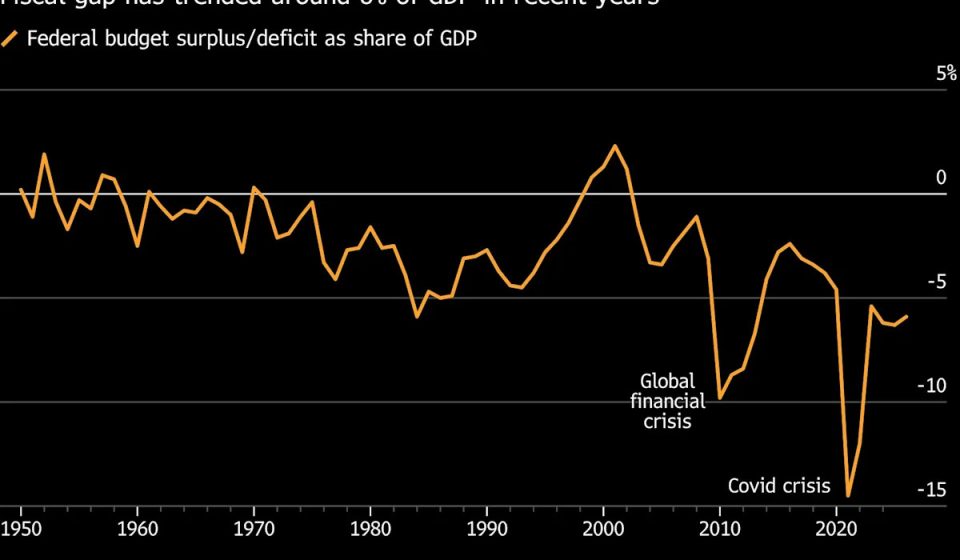
Then there’s the federal government’s $2 trillion budget deficit, the equivalent of about 6 percent of the nation’s gross domestic product, a historically high level of stimulus at a time of low unemployment and solid economic growth. Although the Trump administration has repeatedly pledged to rein in spending, that is unlikely to happen any time soon.

“The macroeconomic backdrop is fraught with risk, which should translate into a healthy term premium,” said Mark Malek, chief investment officer at Siebert Financial. “Every time we make headlines, investors remember this risk.”

–With help from Christopher Anstey.

Most read from Bloomberg Businessweek

©2026 Bloomberg LP

Gn headline

Post Views: 4
Author

adminvoxa

Follow Me
Other Articles
ChatGPT users in Iran published AI-generated articles in US media
Previous

ChatGPT users in Iran published AI-generated articles in US media

CTA worker fatally stabbed at Green Line station, reports say
Next

CTA worker fatally stabbed at Green Line station, reports say

Deliver fast, factual, and easy-to-understand news covering global events, technology, business, science, AI, health, entertainment, and lifestyle.
  • About Us
  • Accessibility Statement
  • Advertise With Us
  • AI Usage & Transparency Policy
  • Contact us
  • Cookie Policy
  • Corrections Policy
  • Meet Our Team
  • Privacy Policy
    • Disclaimer
    • DMCA & Copyright Policy
    • Editorial Policy
    • Ethics Policy
    • Fact-Checking Policy
  • Terms and Conditions
Copyright 2026 — Today's News. Tomorrow's Perspective.. All rights reserved.