Skip to content
-
Subscribe to our newsletter & never miss our best posts. Subscribe Now!
Today's News. Tomorrow's Perspective. Today's News. Tomorrow's Perspective.

Deliver fast, factual, and easy-to-understand news covering global events, technology, business, science, AI, health, entertainment, and lifestyle.

Today's News. Tomorrow's Perspective. Today's News. Tomorrow's Perspective.

Deliver fast, factual, and easy-to-understand news covering global events, technology, business, science, AI, health, entertainment, and lifestyle.

  • Home
  • Breaking News
  • Business
  • Sports
  • Health
  • Politics
  • Technology & AI
  • World
  • Home
  • Breaking News
  • Business
  • Sports
  • Health
  • Politics
  • Technology & AI
  • World
Close

Search

  • https://www.facebook.com/
  • https://twitter.com/
  • https://t.me/
  • https://www.instagram.com/
  • https://youtube.com/
Subscribe
Bank of America Revises Micron Stock Forecast as AI 'Memory Tax' Rises
Business

Bank of America Revises Micron Stock Forecast as AI ‘Memory Tax’ Rises

By adminvoxa
October 4, 2026 4 Min Read
Comments Off on Bank of America Revises Micron Stock Forecast as AI ‘Memory Tax’ Rises

AI companies are forced to think about memory provisioning years in advance, not just when the next server arrives.

As models grow and workloads become more demanding, ensuring sufficient high-performance memory becomes an increasingly important operational and financial constraint. Bank of America calls this growing burden that of AI “memory tax”.

For Micron Technologies (MU), that means higher prices, longer customer commitments and a potentially more sustainable earnings cycle than investors have historically associated with memory chips.

In a note shared with me, Bank of America responded by sharply raising its guidance after another stunning profit, and the reason is far from simple improved results.

BofA says AI allows memory to capture more value, while Micron gains greater visibility through take-or-pay customer agreements.

Why Bank of America predicts a more sustainable Micron earnings cycle

What’s changed for Bank of America isn’t just that Micron has beaten expectations again, as it has for the last four consecutive quarters.

The bank now has better visibility into how long high prices and profitability can last, allowing it to increase its profit forecasts.

BofA pushed back its fiscal 2027 revenue estimate to $275.4 billion out of $230.3 billion and fiscal 2028 sales to $317 billion out of $244.1 billion.

More microns:

EPS estimates soared to $171.78 from $140.24 for 2027 and $197.90 from $145.45 for 2028. He also reiterated his Price target of $1,550while calling Micron one of its top picks in AI.

This belief comes from the fact that demand is becoming increasingly difficult to dismiss as a temporary spike in the memory cycle.

Micron now has 26 strategic customer agreements, up from 16 last quarter, covering approximately 35% of revenue through 2030. More than 75% of fiscal 2027 production is already committed under these agreements and other customer commitments.

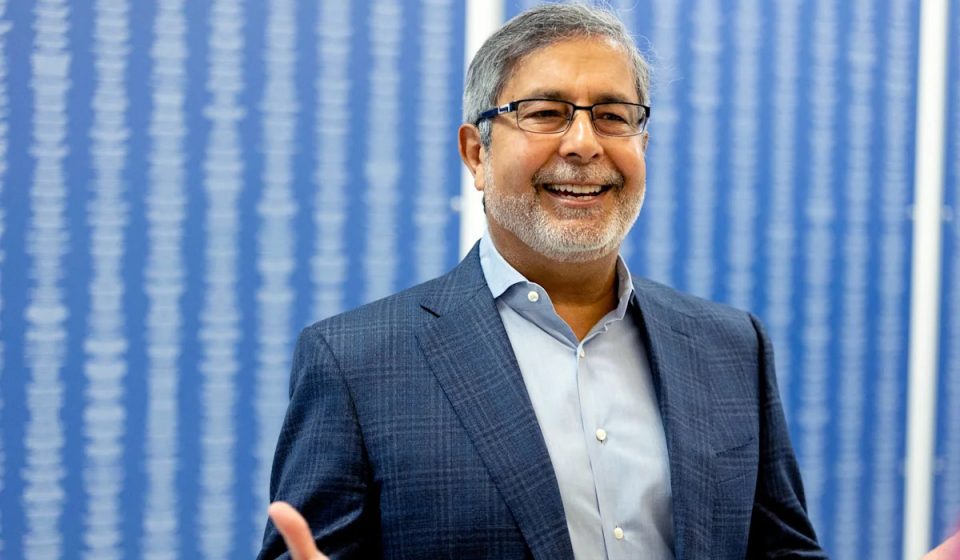
CEO Sanjay Mehrotra went further, saying Micron had “no visibility” on when supply and demand would return to balance. He expects memory requirements in 2027 and 2028 to be stricter than in 2026, as larger AI models, longer context windows, and greater concurrency consume more memory.

Investors were initially hesitant after the earnings, with Micron falling about 4% before reversing to finish up about 3%.

This shows that even though Micron has killed it from an earnings outlook perspective, investors still need to decide how much of this AI-driven pricing power is truly structural rather than cyclical.

Bank of America Revises Micron Stock Forecast as AI 'Memory Tax' Rises
Bank of America revises Micron’s earnings outlook as demand for AI memory rises.OLIVER CONTRERAS/Getty Images

Micron’s cash flow could be the clearest sign this cycle is different

What impresses me about Micron’s quarter isn’t just its incredible $54.2 billion in revenue or its record gross margin of 87%. This is what these numbers now produce under the income statement.

Micron generated $44 billion in operating cash flow and $33.2 billion in free cash flow during the fiscal fourth quarter, while ending the quarter with $73.5 billion in cash and investments and a net cash position of $68.3 billion.

Chief Financial Officer Mark Murphy said the balance sheet has “never been stronger,” even as Micron prepares to increase spending on technology and capacity.

I think the most important detail is where some of this visibility comes from.

Micron received $12.3 billion in customer cash deposits during the quarter, while its 26 strategic customer agreements now represent approximately $150 billion in remaining performance obligations under agreements with defined pricing frameworks.

These are buy-or-pay contracts, giving Micron something that memory makers have historically lacked: clearer visibility of demand before committing billions to new manufacturing capacity.

This explains why Bank of America sees potential to dramatically increase capital returns, estimating that buybacks could eventually reach $60 billion to $100 billion in the 2028-2029 fiscal year, although management has not yet clarified the level of buybacks in the near term.

I wouldn’t treat customer deposits as free money because they are ultimately credited back to purchases. But combined with record profits, committed production and long-term contracts, they suggest Micron is financing its expansion from a considerably stronger position than in past memory cycles.

Micron’s valuation still leaves room for the earnings story to do the job

To me, the most attractive aspect of Micron’s setup is that its valuation hasn’t grown as quickly as its earnings power.

The stock trades at about 6.2 times forward non-GAAP earnings, compared to an industry median of 23.7 times, a discount of nearly 74% based on Seeking Alpha data.

Additionally, Wall Street is starting to react.

I recently explained that Rosenblatt reshuffled his target from $1,500 to $1,900, while DA Davidson increased his target from $2,000 to $2,100 and Mizuho increased his target from $1,300 to $1,400.

Still, I wouldn’t interpret the low multiple as automatically making Micron cheap. Memory stocks historically trade at compressed earnings multiples near strong periods in the cycle because investors fear earnings will eventually normalize.

This is exactly why Micron’s customer commitments, tighter supply outlook and growing exposure to AI are important. If these factors make earnings more sustainable than previous cycles, the current multiple could value Micron like the old company, even if its economic situation becomes significantly different.

Related: 5-Star Analyst Reset Micron Stock Target After $37.7 Billion Windfall

This story was originally published by The street on October 3, 2026, where he first appeared in the Invest section. Add TheStreet as Favorite source by clicking here.

Gn bussni

Post Views: 4
Author

adminvoxa

Follow Me
Other Articles
Shooting near Cal State Northridge campus leaves 2 dead
Previous

Shooting near Cal State Northridge campus leaves 2 dead

Tech companies launch cuddly mascots to ease AI anxiety
Next

Tech companies launch cuddly mascots to ease AI anxiety

Deliver fast, factual, and easy-to-understand news covering global events, technology, business, science, AI, health, entertainment, and lifestyle.
  • About Us
  • Accessibility Statement
  • Advertise With Us
  • AI Usage & Transparency Policy
  • Contact us
  • Cookie Policy
  • Corrections Policy
  • Meet Our Team
  • Privacy Policy
    • Disclaimer
    • DMCA & Copyright Policy
    • Editorial Policy
    • Ethics Policy
    • Fact-Checking Policy
  • Terms and Conditions
Copyright 2026 — Today's News. Tomorrow's Perspective.. All rights reserved.