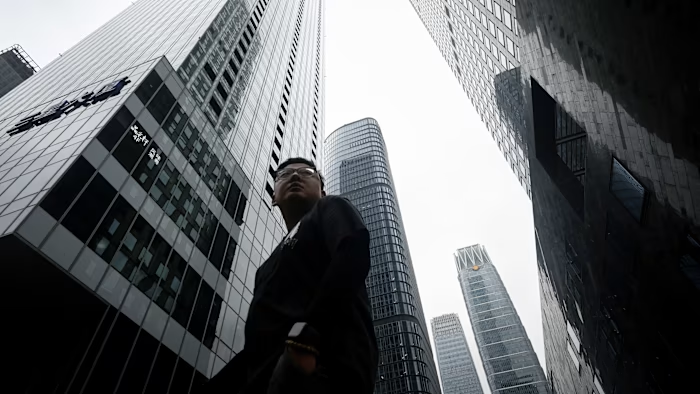

China’s growing debt limits the government’s fiscal capacity to implement new stimulus measures to revive flagging domestic demand and bolster economic growth, public finance studies show.
Debt service payments alone are expected to account for 19.2 percent of the central government’s overall public budget this year, up from 12 percent in 2014, according to a new Conference Board study.
The problem is particularly acute at local government level, where debt interest payments have increased by 16 percent per year over the same period.
Together, central and local government debt interest payments are expected to amount to RMB 1.4 billion ($209 billion) in 2026, up from about RMB 348 billion in 2014.
“Debt servicing is becoming a significant constraint on fiscal space at the local level,” said Yuhan Zhang, senior economist at the Conference Board’s China Center.
China’s debt has risen rapidly in recent years due to its investment-led growth model, which relies on state loans and incentives for government-favored projects. The public debt-to-GDP ratio is expected to reach 122% by the end of 2026, an increase of 48 percentage points from its pre-pandemic level, according to analysts at Morgan Stanley.
Beijing has pledged to do more to boost moribund domestic demand, as a five-year slowdown in the real estate sector has depressed the finances of households and local governments.
Economic growth fell to 4.3 percent in the second quarter, below the official target of 4.5 to 5 percent for the full year, due to weakening retail sales and a sharp decline in investment in fixed assets.
China unveiled some measures late last month, including subsidies for mortgage interest payments and interest reductions on a financing facility, days after the State Council, or cabinet, called for “stepping up” efforts to “implement countercyclical adjustments in macroeconomic policies.”
Chinese authorities have also stepped up efforts to claw back taxes on interest and dividends earned by offshore trusts, strengthening the government’s coffers by putting pressure on its richest citizens.
But several analysts question the impact of the stimulus measures. Barclays described the measures as “a nudge, not a game-changer”, while Goldman Sachs estimated they amounted to a “small” fiscal subsidy of up to RMB100 billion over five years.
“In our view, this policy is unlikely to meet investors’ expectations,” said John Lam, head of China and Hong Kong real estate research at UBS, pointing to the cap on housing values at RMB 1.5 million.
And as Chinese export growth, particularly in AI-related electronics, continues to accelerate, Beijing has indicated it will prioritize investment in cutting-edge technologies over setting aside large sums for recovery, as it vies with the United States for supremacy in emerging industries.
“We must…continuously develop and strengthen the high-tech industry, (and) improve the level of self-reliance,” President Xi Jinping said in instructions delivered to the National High-Tech Industry Conference in Beijing last month.
Economists say that if Beijing wanted to implement a determined recovery plan, it could issue additional bonds to the central government, seen as less indebted than local governments.
But Chinese leaders may be reluctant to apply more pressure. While the central government runs a budget deficit of around 4 percent, the increased deficit, a broader measure of state spending, amounts to around 10 percent of GDP, according to Goldman Sachs.
Since the real estate crisis, the central government has also had to transfer increasing amounts of revenue to lower authorities, which previously depended on land sales for growth.
“Spending on debt interest payments increased 341%” between 2013 and 2025, according to the Washington-based Center for Strategic and International Studies, “faster than any other major budget category.”
The think tank noted that about 14 percent of U.S. government spending went toward interest payments this year, while Japan, one of the world’s most indebted governments, spent nearly 26 percent.
The Conference Board’s Zhang noted that the budget included targeted fiscal support for science, technology and other strategic priorities “rather than a large-scale stimulus package aimed primarily at boosting short-term growth.”
Among central government spending, which accounts for 15 percent of the general public budget, military spending accounts for 42 percent, up from almost 36 percent in 2014, while the shares of science and technology, education, general public services, social protection and employment all declined slightly.
Social security spending by local governments has also increased to around 18 percent as China’s population ages. Health spending has also increased slightly.
Economists said that instead of additional stimulus measures, Beijing is urging local governments to accelerate allocated budget spending this year. Local government budgetary spending was slower than expected in the first half of the year.
“The policy response will be to accelerate the pace of implementation, but this will remain within the fiscal budget allocated at the start of the year,” said Robin Xing, chief China economist at Morgan Stanley.
Gn bussni