Nike Stock’s Misery Continues After Another Quarter and Terrible Outlook: Wall Street Reacts

Nike (NKE) reminded investors why the stock is trading at record highs on its earnings day.
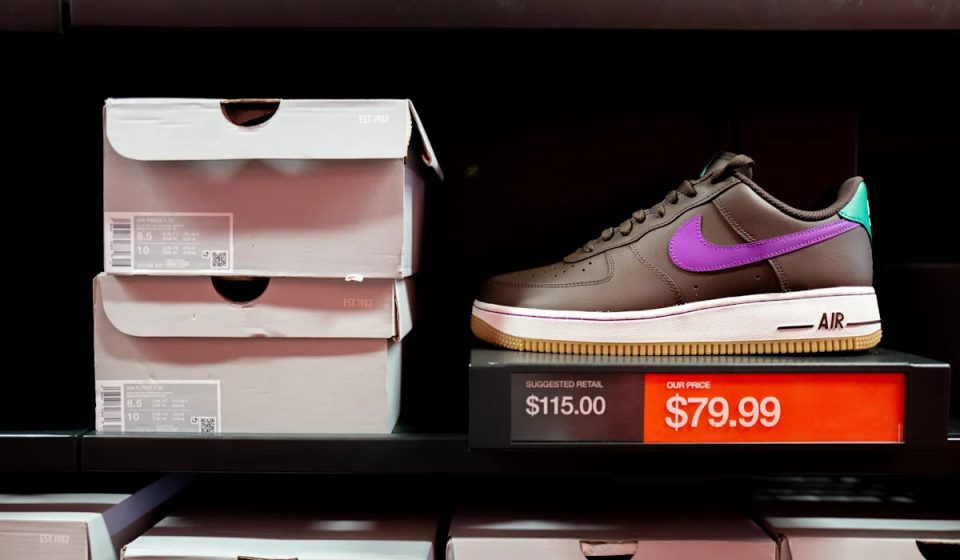
Shares of the fallen sportswear giant fell 6% in early trading Friday, extending the slide for a stock that had already fallen 76% in just the last five years.
33.41 -1.74 (-4.95%)
At 1:38:44 p.m. EDT. Open market.
Nike’s quarterly earnings and results announcement was fraught with alarm about the depth of the business slump and the difficulty of the road to recovery:
🛑 Nike brand sales: down 4%
🛑 Online sales: down 13%
🛑 Converse sales: down 28%
🛑 Sales in China: down 26%
🛑 Stock: down just 3%
🛑 Reported a major wave of layoffs (again)
🛑 Sales fell by a high single-digit percentage in fiscal 2027
🛑 Earnings forecast well below consensus ($1.15 to $1.35 vs. estimates of $1.66)
“Overall, there is a lack of energy in the lifestyle industry right now, which is impacting traffic. Yes, the consumer is cautious. But as an industry leader, it’s up to us to bring more creativity to sportswear,” Nike CEO Elliott Hill said on the earnings conference call.
Here’s the neighborhood vibe and Wall Street outlook.
“We are not yet ready to bottom with shares trading at 28x P/E at the midpoint of FY27E guidance. The new Pace cost savings plan is helping, and we expect it to be increased at November’s investor day, helping chart a path to a more tangible margin structure relative to EBIT MSD% margin in FY27E. We recommend athletic shoe brands challenger while NKE is out of the game (DECK, ONON, WWW). – Peter McGoldrick, analyst at Stifel
“NKE’s first quarter confirmed that the turnaround is underway, with performance continuing to grow while North America trends improve and profitability shows signs of stabilizing. As China, Jordan and sportswear continue to weigh on results, management’s deliberate actions and revised framework for FY27 suggest a greater focus on long-term rebuilding of the brand and market health. – Randy Konik, analyst at Jefferies
“With yet another downward revision, the question remains whether the forecast reductions will represent a band-aid or a slow hemorrhage as they continue to debate the path forward for potential stabilization. With November’s analyst day ahead, we could assume that management probably preferred to brush off the “bad news” to deliver a more positive tone in person, but there is clearly plenty of “bad news” to spare. Mindful of the continued noise, we are lowering our price target at $50 (up from $60) And while that’s certainly not easy (and it certainly hasn’t been correct), we maintain our buy rating amid increasingly negative sentiment and a potential emerging catalyst (potentially hollow estimates, new CFO, November analyst day). -Siméon Siegel, analyst at Guggenheim
Gn bussni