
One of the selling points of ETFs is that they can be very tax efficient for managing capital gains and losses, but wealthy investors may need to rethink some ETF tax deferral strategies following recent communications from the Internal Revenue Service and the U.S. Treasury.
The problem concerns some use cases of Section 351 exchanges, in which wealthy individuals, through an intermediary, create new ETFs with a basket of highly valued stocks. The intention is to defer capital gains tax – which remains a legitimate strategy, but with additional caveats, according to new guidance from tax authorities.
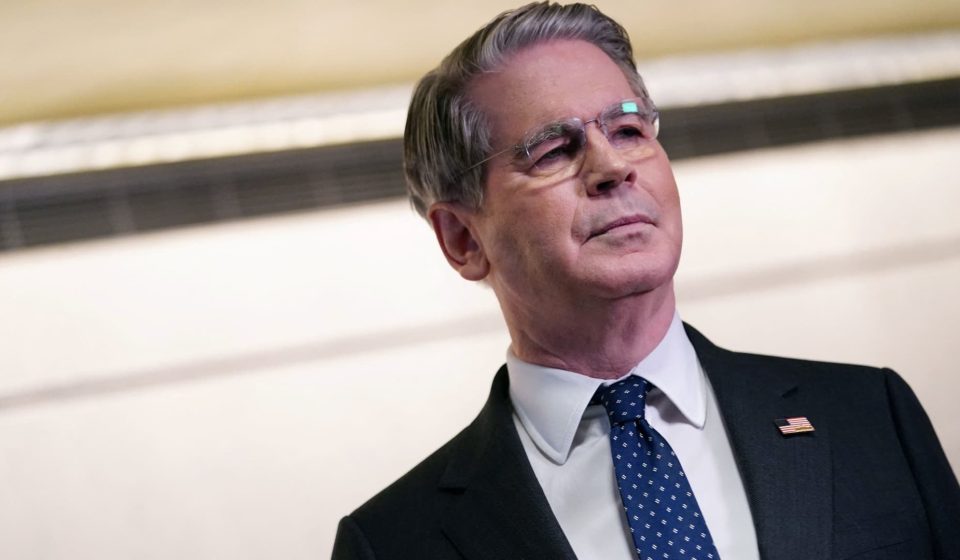
Treasury Secretary Scott Bessent said in an article earlier this week that the guidance “makes clear that Treasury is serious about cracking down on transactions intended to evade taxes or exploit our federal tax code.”
He added of a follow-up IRS ruling on Section 351 ETF conversions designed to avoid tax: “Our message on these conversions is clear: They do not work under current law.”
The combined effort covers cases that tax authorities find troubling, including when an ETF is “merely a conduit” for transferring securities in an attempt to avoid tax. A tax ruling is an official interpretation of a specific set of facts by the IRS, in relation to the tax code and regulations, useful in anticipating the agency’s tax treatment. An opinion, on the other hand, provides more general guidance for broader circumstances.
Section 351 of the tax code generally allows investors to transfer property to a corporation in exchange for its stock without recognizing a capital gain, under certain conditions. For example, no single asset can exceed 25% of the portfolio value, and the top five holdings cannot exceed 50% of the overall value, according to Kitces.com. This is still a generally accepted practice.
“The IRS and Treasury are focusing on tax strategies that they view as abusive practices,” said Jeffrey Colon, a law professor at Fordham Law who specializes in tax law and policy.
By inappropriately avoiding gains, tax authorities say, investors are going against the intent of the rules.
For high-net-worth investors, and their investment and tax advisors, who have turned to ETFs as a tax shield, the landscape is expected to change following new guidance from tax authorities.
Why the tax authorities raise eyebrows
The IRS revenue ruling involved a transfer of a portfolio of securities to a newly created ETF. As part of the planned transactions, the ETF distributed the tendered securities shortly thereafter, and the investor was left with a “materially different” portfolio, without recognizing any gains embedded in the original securities.
“It’s really about getting diversification without paying taxes,” said Brian Gray, a tax partner at Gursey Schneider.
Tax authorities said this was a problem, but the problem didn’t come out of nowhere.
A Bloomberg analysis last July found that a total of $22 billion in ETFs had been created for this purpose, deferring up to $6.5 billion in capital gains, with activity accelerating significantly since 2024.
“Tax rules should reward investment, not abusive financial engineering,” Bessent said in a July 22 article on
He referenced that July warning in his message this week.
IRS and Treasury officials met in July with members of the Wall Street Tax Association to discuss the types of transactions the government is interested in, including questionable Section 351 trades.
The advisory addresses many of the strategies discussed.
Who uses 351 exchanges? These are mainly the very rich
Typically, only people with higher incomes use Section 351 exchanges.
Costs are one reason. Creating an ETF can cost $200,000 to $300,000, said John Pantekidis, managing partner and general counsel at TwinFocus in Boston. Some firms suggest that investors should have at least $25 million in appreciated stocks to include in the ETF for it to be a viable option, but Pantekidis sets the bar even higher, saying it doesn’t make sense for anyone with less than $100 million in stocks.
The Notice does not imply that all Section 351 transactions are suspicious.
“This notice does not address or express any opinion regarding transactions in which a Section 351 transaction is used to seed a newly created ETF with assets that are consistent with the ETF’s investment thesis and that are intended and expected to be retained by the ETF absent a material change in circumstances,” the notice states.
Indeed, there may be valid reasons for wealthy individuals and families to complete a Section 351 exchange, said Joshua Norman, principal in Cerity Partners’ Bardstown, Ky., office. For example, a wealthy person might want to gift shares of an ETF to another person who doesn’t want individual shares. Additionally, converting separately managed accounts to ETFs can reduce the ongoing tax burden on high net worth individuals, thereby improving after-tax returns.
Some ETF experts believed that this language in the opinion could lead to even more widespread use of the strategy. “Non-consensus view: Regulators opened the door this week for well-designed 351s to enter the mainstream market,” wrote Mel Faber, founder of ETF manager Cambria Funds, who provided an overview of the strategy to investors.
ETF Questions Remain
Tax regulators impose additional restrictions for the transfer to be considered a tax-deferred transfer.
“Timing is also key,” Norman said.
The tax regulators’ notice clearly states that transactions that occur “shortly after” the contribution of appreciated securities are suspicious.
But the IRS has not clarified what that means, leaving tax and legal professionals to expect additional guidance.
The “soon after” duration will remain a gray area until tax regulators issue additional guidance, Norman said.
Other tax experts shared this view.
“Regarding Treasury’s revised §351 regulation for seeding ETFs, I view 3 elements as evidence of aggressive planning…1) evidence of a plan 2) prompt redemption after seeding 3) a significantly different portfolio than contribution. This leaves a lot of gray area and I think we will see a lot of ‘facts and circumstances’ analysis in the months/years to come,” Brent Sullivan, a tax analyst who runs Tax Alpha Insider, a blog devoted to taxes and portfolio strategies, wrote on X.
The IRS and Treasury are seeking comments on the notice by October 28.
One thing regulators won’t do is eliminate the idea of swapping securities for stocks, because all major ETFs rely on redeeming and creating shares that are tax-free as part of their day-to-day operations. “It’s a multi-billion dollar industry,” Pantekidis said.
However, they will likely provide more safeguards for small ETFs that create units and immediately diversify their portfolios to benefit from tax advantages, he added.
Additional tax strategies could be targeted
Tax authorities are also taking a closer look at additional strategies, according to the notice. These include transfers to partnerships in Section 351 conversions and ETFs that use “box spread” strategies, which involve options and allow investors to defer capital gains.
“Tax professionals need to understand these strategies being put forward to advise clients on emerging audit risks,” Ed Zollars, a tax partner at the accounting firm Thomas, Zollars & Lynch, wrote in a blog post.
Congress could also decide to intervene to make certain changes to existing ETF regulations. For example, they could limit ETF profits by distributing appreciated securities, Colon said.
Gray suggests investors looking to manage capital gains taxes consider an exchange fund instead. It is a private investment vehicle, typically structured like a limited partnership, that allows investors with concentrated, appreciated stock positions to pool their shares into a diversified portfolio, while deferring capital gains taxes. One drawback is the seven-year holding period participants have to redeem their shares.
Investors can also use a charitable remainder trust to manage capital gains and losses, he said.
Gn bussni