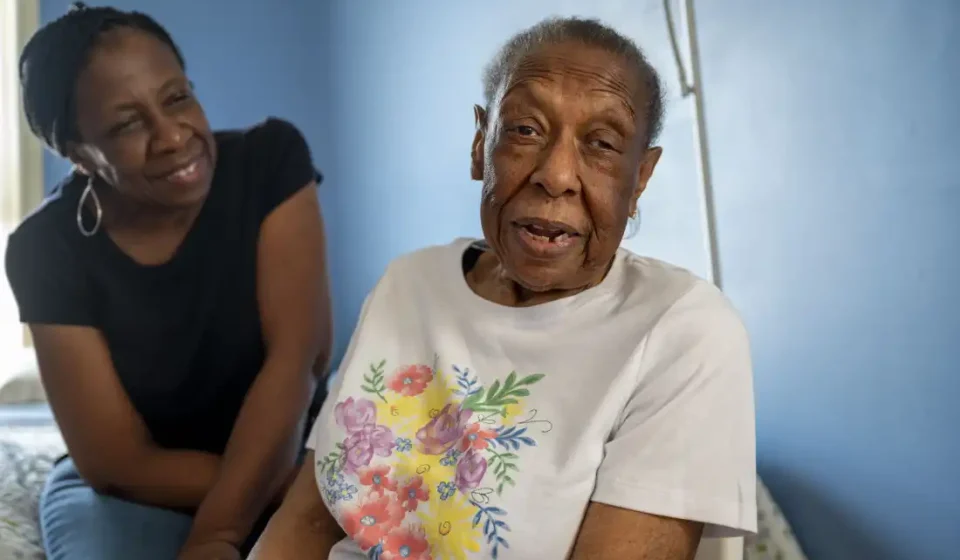
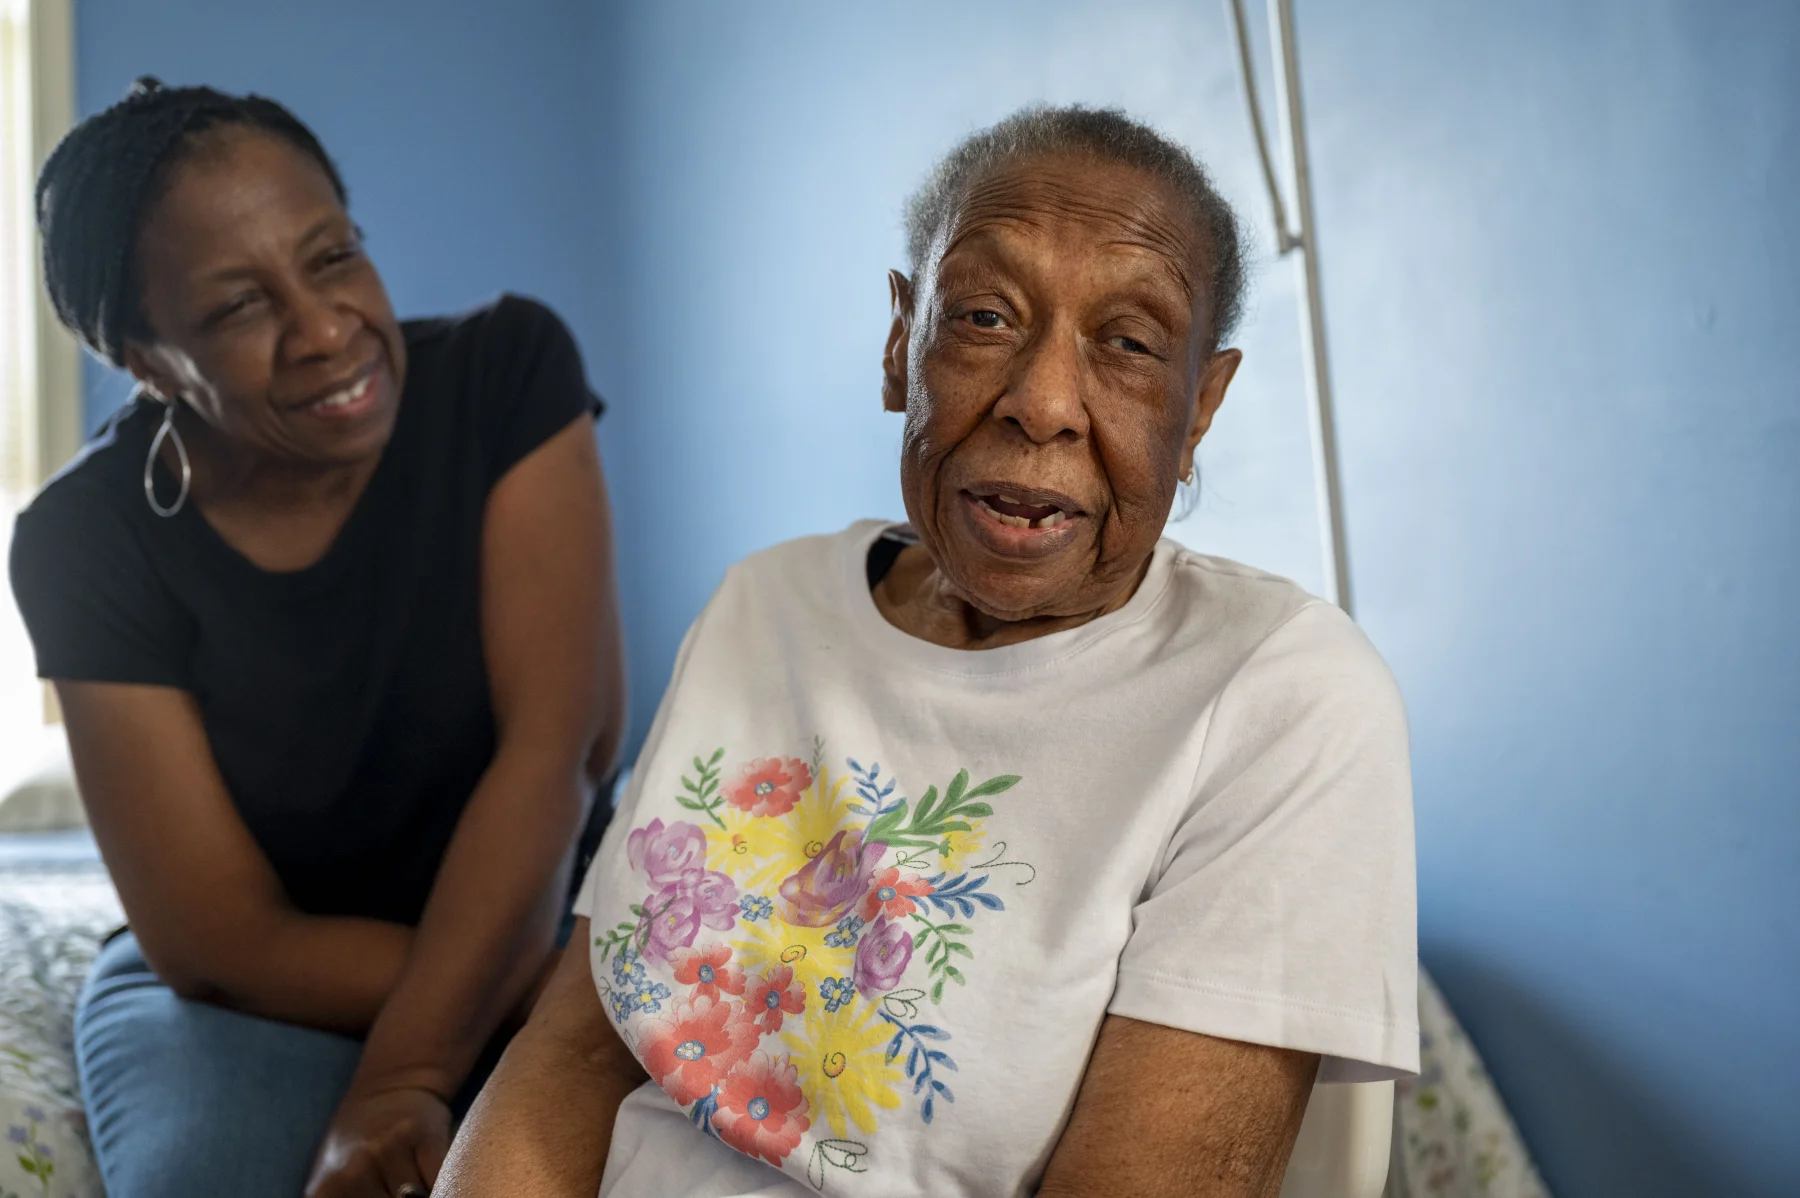
Cookie Jones, left, quit her job to care for her mother who had Alzheimer’s disease. Caregivers often earn less because they take time off work to help their aging family members.
Tyler Russell/Connecticut Public via Getty Images
hide caption
Tyler Russell/Connecticut Public via Getty Images
As prices have risen in recent years, the cost to caregivers has skyrocketed. A study released Wednesday by AARP finds that family caregivers — people helping disabled, chronically ill or elderly adults — now spend an average of $11,508 out of pocket each year. That’s about 60% more than just five years ago and represents on average 31% of a caregiver’s income.
The increase during those years is more than twice the overall inflation rate of 24 percent, as measured by the federal Bureau of Labor Statistics’ Consumer Price Index.
What is driving this rise in power? Food, housing and medical expenses account for the largest share, according to the study, which surveyed 2,538 family caregivers.
In other words, just the basics.
The rising costs come as family caregivers take on more care and more complicated medical responsibilities at home, says Megan O’Reilly, vice president of government affairs at AARP. “The more care it takes, the more it costs.”

And increased spending is only part of the problem. The demands of caregiving often force people to reduce their work hours or stop working altogether, the survey found. It’s a double whammy: increased costs on top of lost revenue.
Growing demands, falling incomes
Meghan Maher saw it with her own eyes. Just seven weeks after the birth of her first baby, her mother was diagnosed with advanced cancer. Suddenly, Maher became a “sandwich” caregiver – parent and child needing her at the same time.
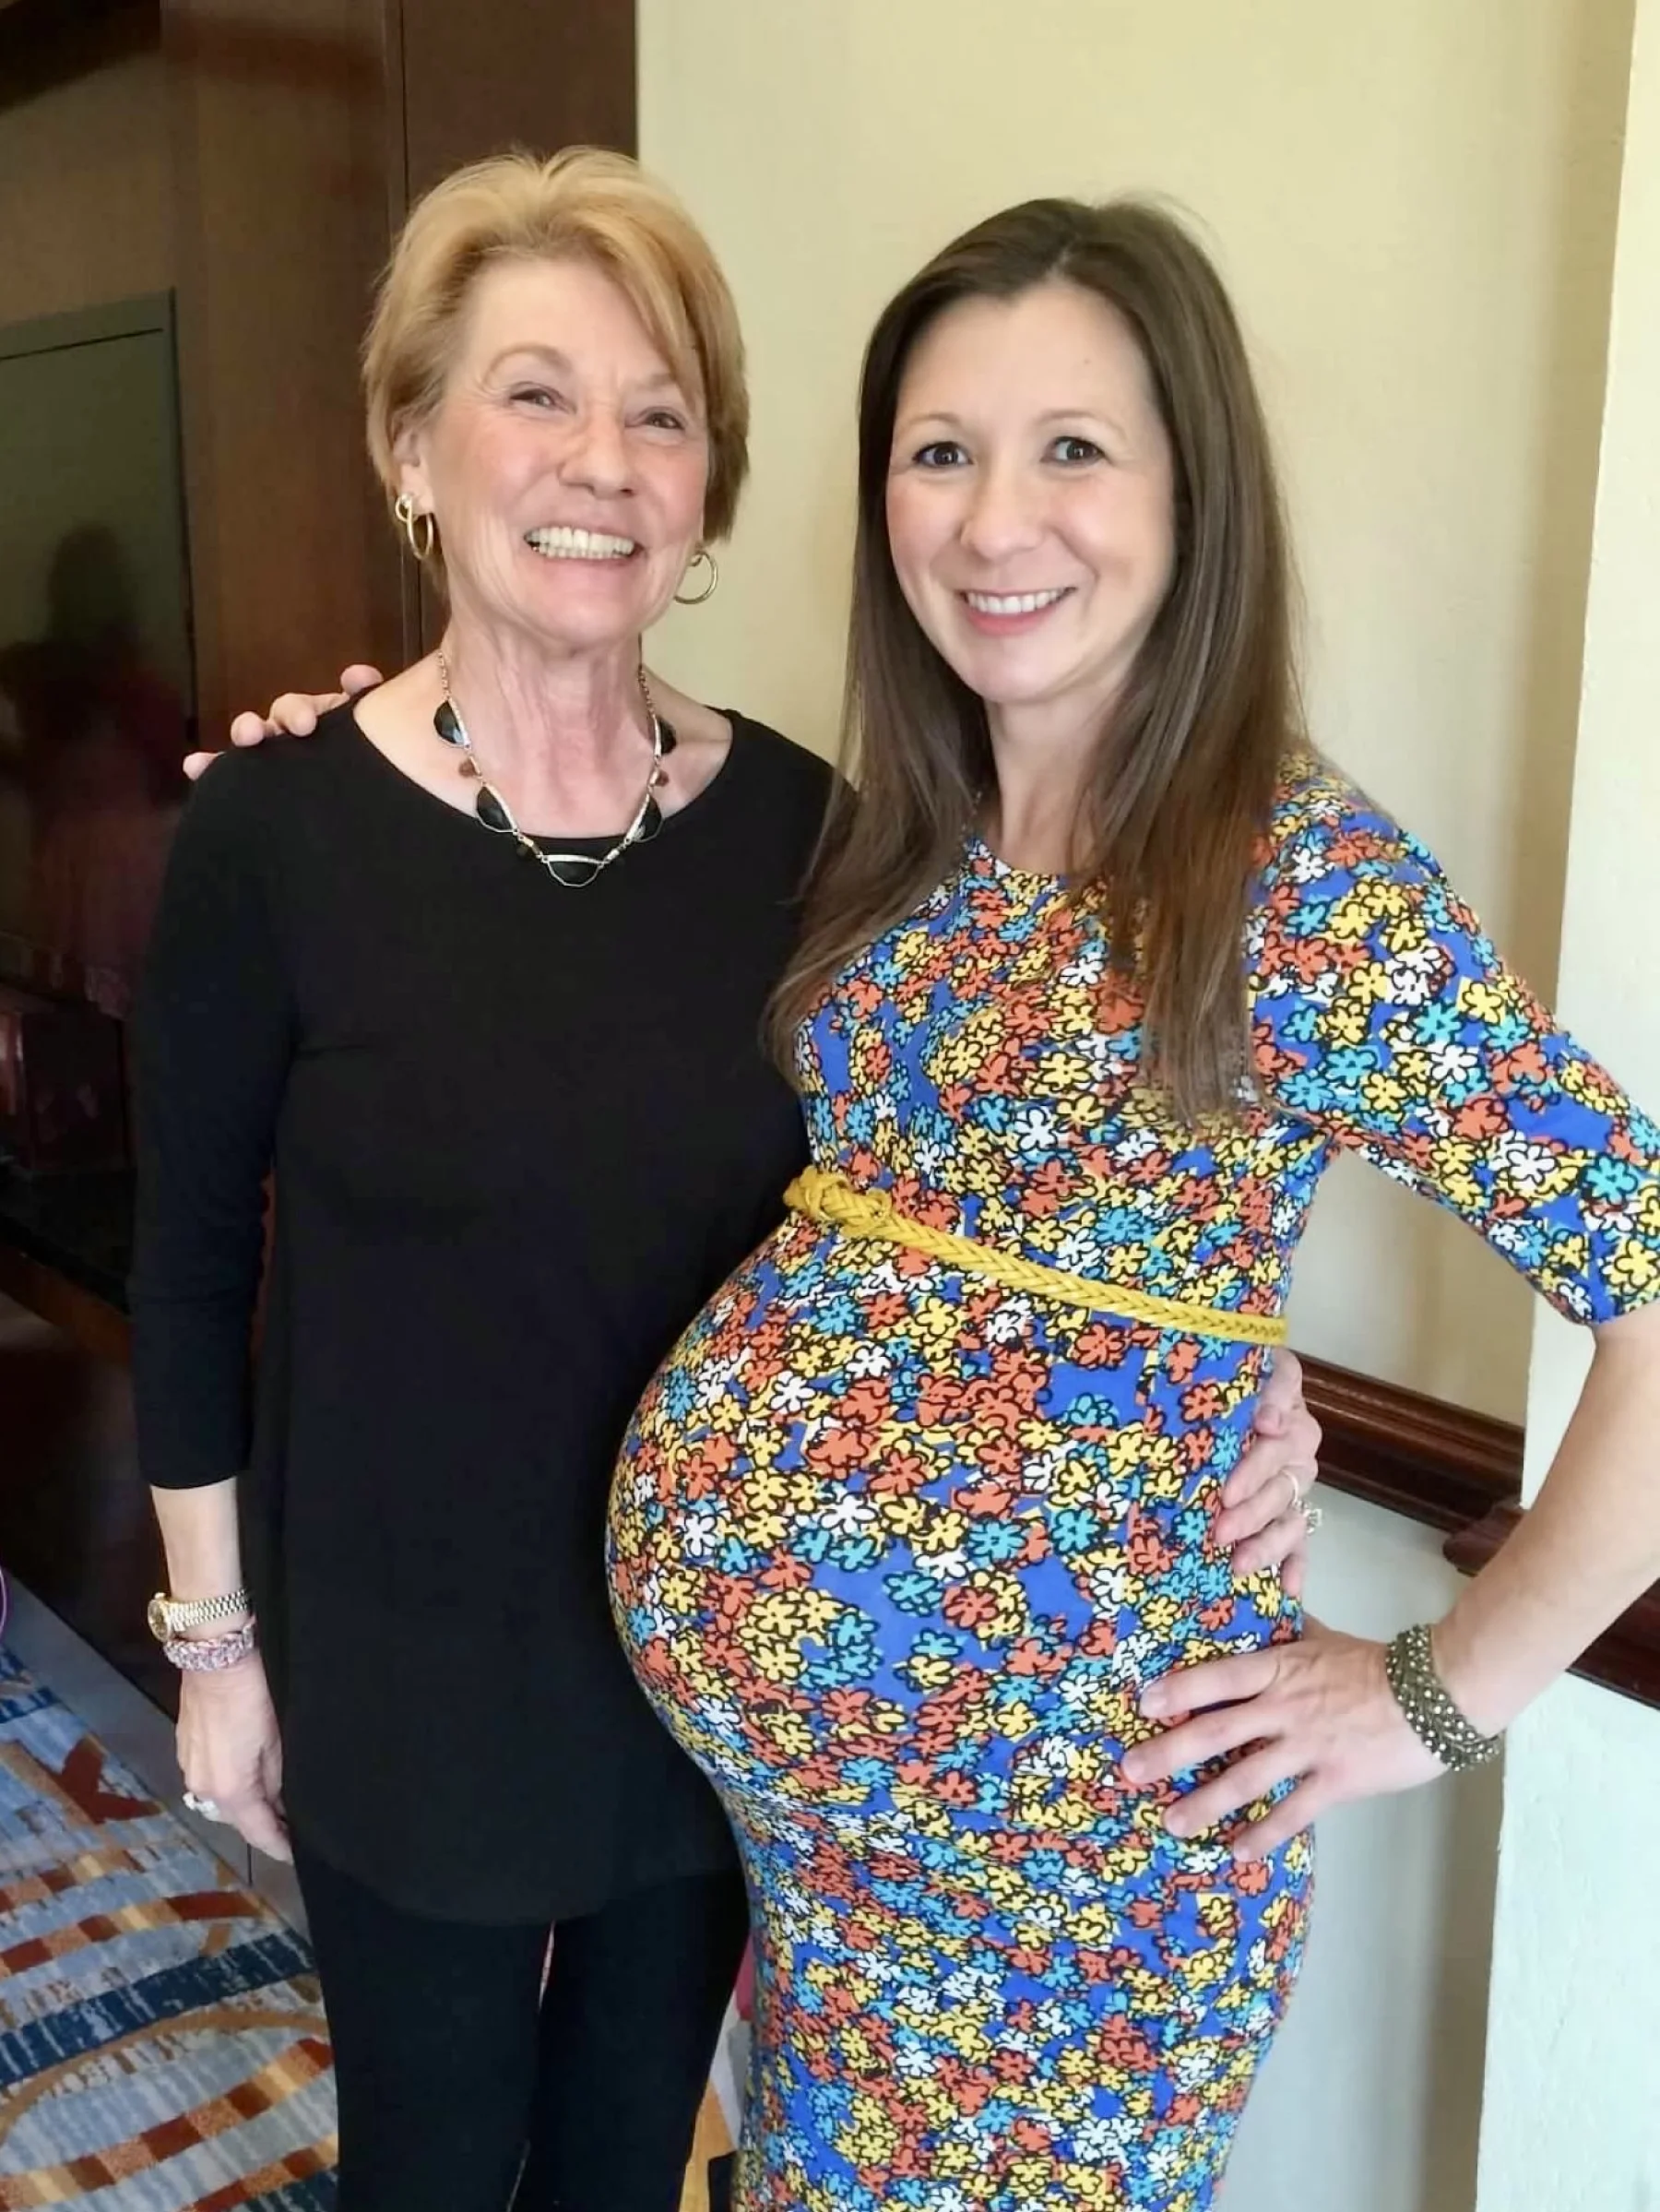
Meghan Maher and her mother Connie Cadwell. In order to help his mother undergo cancer treatment and care for her young children, Maher had to give up his career.
Maher family
hide caption
Maher family
At first, she tried to manage everything. She returned to her career in cancer research after maternity leave, but coping with the demands of work, mother and newborn son was too much.
She reduced her hours to part-time. But even that was not manageable. There was no way to attend all of her mother’s appointments, coordinate her care, and also be available for big deadlines at work.
She resigned and the family’s income dropped by half. Because her husband had a good job, they didn’t struggle, but “it was really scary,” she says now. As her mother became ill, her parents moved in, increasing household expenses.
Shortly after his mother died in 2017, his father had a series of major complications from abdominal surgery and was seriously ill for months. Maher needed to be by his side during hospital stays, defending him at all times, so now the family also had to pay for child care. She estimates the cost at around $10,000 per year.
His father eventually recovered and the family was able to get by despite the difficulties. Many are not so lucky.
According to the AARP report, about half of family caregivers say they have made significant financial sacrifices: working more hours, reducing savings or even dipping into money set aside for retirement.
More caregivers, higher bills
Many Americans face the cost of care, and more will in the future. About 63 million people now provide ongoing help to a family member or friend, or about 1 in 4 adults. The need will likely grow: an estimated 70 percent of people who turn 65 today will need some form of help as they age.
Medicare does not pay for routine care, either at home or in a facility, and such care is expensive. By 2025, 40 hours of home care per week cost about $72,792 per year, according to insurance company Genworth, which conducts annual cost-of-care surveys. Skilled nursing care costs an average of $115,000 per year for a shared room.
When Maher returned to work, she became a professional death doula. This means she helps her clients navigate the emotional and practical challenges of end of life. She is self-employed, so she can control her own schedule and limit the number of clients she serves. This gives him the flexibility to help his father as he gets older. But his income is half of what it would have been in his old career.
With the clients she helps, she sees other ways the costs of care add up. In Florida, where she lives, it’s common for people with chronic illnesses to hire a lawyer in order to qualify for Medicaid, which, unlike Medicare, pays the bill for long-term care. Even if they qualify for benefits, the paperwork is so complex that they end up paying for legal help to navigate it. In Florida, she said, it costs about $6,000.
What she saw and experienced motivates her to draw attention to the difficulty of caregiving. In April, Maher testified before Congress before a Senate Special Committee on Aging. “Caregiving has also reshaped my professional life,” she told the Senate. “The flexibility of self-employment comes with real financial and professional compromises.” She was invited by Daughterhood, an organization that provides support and resources for caregivers.

Family carers can access some of the public money, depending on where they live. All states pay some types of family caregivers through Medicaid. In California, for example, more than 800,000 caregivers earn between $16.90 and $25 an hour working from home. Funds for these programs will likely decline due to President Trump’s budget bill that cut nearly $1 trillion in Medicaid funding over the next decade.
If the person needing care is eligible for Veterans Administration benefits, they may also be eligible for financial assistance to cover the cost of care. Like Medicaid, the rules are complex, and many family caregivers hire attorneys to advise them on eligibility and the application process.
More support on the horizon?
The cost of care hasn’t been as visible as the cost of gas, food and health care, says Nancy LeaMond, executive vice president of AARP. She thinks that will change. “When you see the number of people paying that kind of money, I think it will provide impetus for action in the legislative area.”
In recent years, Congress has introduced various proposals that could put money back in the pockets of caregivers, such as allowing caregivers to spend money in their health savings accounts tax-free on their parents’ medical expenses. In some states, new rules are already a reality.
Six states now offer tax credits to family caregivers for expenses such as renovating a home with grab bars or guardrails, typically between $1,000 and $5,000 a year. Two other states have more limited programs. Last year, two U.S. senators introduced a bipartisan bill that would establish a similar $5,000 tax credit nationwide.
In 14 states and the District of Columbia, most employers are required to provide paid family and medical leave. These policies include time off to care for a family member. Another bill introduced in Congress would turn this into a national policy that would require up to 12 weeks of partially paid leave for some workers.
A third federal bill would protect Social Security benefits for caregivers. Under current rules, a person who stops working to care for their family full time sees their future Social Security check shrink because they no longer earn credits toward retirement. This bill would change the law to continue to award points to full-time caregivers.
“We spend a lot of time talking to members of Congress, and you can’t bring this up in a meeting without being interrupted by someone telling their own story,” LeaMond says. “Over time, I believe this will come together to support family care.”
Kat McGowan is a freelance journalist covering adult care and reporting on the series “What it takes” for NPR.
Gn headline