
The United States produces more crude oil than ever. According to the Energy Information Administration, US crude production on track to reach record average 13.8 million barrels per day in 2026, surpassing the previous record set last year.
Yet diesel prices have recently reached record highs, while distillate inventories remain exceptionally low. The EIA expects These stocks will remain below the five-year range for much of 2027, with stocks falling below 100 million barrels for the first time in more than two decades. At first glance, this seems contradictory. If the United States has more oil than ever, why can’t refiners just produce more diesel?
The answer is that crude oil and diesel are not interchangeable products. Oil must pass through a refinery before becoming diesel, gasoline, jet fuel, heating oil, or any of the many other petroleum products actually used by consumers. A record amount of crude oil can be produced while markets for refined products remain tight because a bottleneck may occur once the oil comes out of the ground. Nowadays, this is increasingly the case.
A barrel of oil is not a barrel of diesel
One of the most enduring misconceptions about oil markets is the assumption that refiners can decide how much gasoline or diesel they want to produce and simply adjust their production accordingly. They have a certain degree of flexibility, but this is limited by chemistry, crude quality, refinery configuration and the equipment installed at each facility.
A typical 42-gallon barrel of crude processed in a U.S. refinery produces approximately 19 to 20 gallons of gasoline and 11 to 13 gallons of ultra-low sulfur distillate, most of which becomes diesel or fuel oil. The rest becomes jet fuel, petrochemical feedstocks, asphalt, petroleum coke and other products.
In 2025, distillates represented approximately 30% of the total yield of American refinerieswhile finished gasoline accounted for almost 46%. These proportions may change somewhat as refiners change their operating conditions, process different crude oils and respond to market prices, but a refinery designed to produce about 30% distillate cannot simply double that share because diesel prices are high.
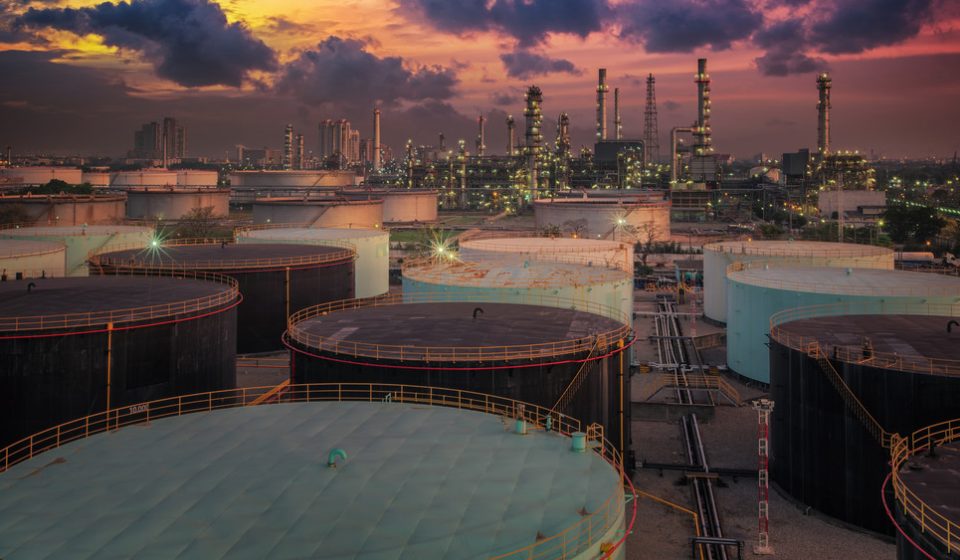
Modern refineries are extremely complex systems of distillation towers, catalytic crackers, hydrocrackers, cokers, hydrotreaters, and other processing units. Each was designed around particular crude lists and product markets, and while operators can optimize within these constraints, there are limits to the extent to which the product mix can be changed. That’s why the diesel shortage can’t be solved simply by pointing to record crude production and asking refiners to produce more.
Refiners are already working hard
There is also a practical limit to how much additional diesel U.S. refineries can produce when utilization is already high. In the third quarter, American refineries would have operated at an average of around 96% of capacity, as companies responded to very high refining margins. Diesel crack spreads, which measure the difference between the value of diesel and the crude oil used to produce it, have reached extraordinary levels as global product supplies have tightened.
When refineries are operating around 90%, there is very little spare capacity available to bring into service. Plants also cannot operate at maximum rates indefinitely, because maintenance is unavoidable and fall is traditionally a major turnaround season for refineries. Operators can defer some maintenance work when margins are attractive, but units ultimately must come down for inspections and repairs.
Total U.S. refining capacity also slipped slightly. The EIA reports that operational crude atmospheric distillation capacity stood at about 18.2 million barrels per day at the start of 2026, down about 250,000 barrels per day from the previous year, with 130 operational oil refineries remaining in the country. This is not evidence of a catastrophic collapse of U.S. refining, as existing refineries have expanded significantly over time, but it does mean that there is not a huge reserve of spare capacity waiting to replace lost global supply.
Building additional capacity is also very different from drilling another oil GOOD. A major refinery expansion can require billions of dollars, years of engineering and construction, lengthy permitting and certainty that the investment will remain profitable for decades. This is a difficult commitment to make in a sector where demand growth, environmental policy, electrification and energy efficiency standards all introduce uncertainty about long-term returns.
The shortage is global
Nor can the current diesel problem be understood by limiting ourselves to the case of the United States. The EIA says U.S. distillate stocks fell below their five-year range in April as significant supplies disappeared from the Middle East, Russia and China. American refiners responded export more fuel in a global market willing to pay high prices, and net distillate exports are at or near a five-year high through much of 2026.
Russia has restricted its fuel exports because Ukrainian attacks damaged parts of its refining system. Refinery production and transportation in the Middle East have been disrupted by the Iranian conflict, while China has suspended most of its fuel exports for October as domestic refiners work to replenish depleted stocks. Taken together, these developments have tightened diesel availability in several major regions at the same time.
Europe is particularly exposed because the continent has steadily reduced its refining capacity over the past fifteen years. European and neighboring refining capacity has fallen from around 17.5 million barrels per day in 2009 to around 14.4 million barrels per day today, increasing dependence on imported refined products. When multiple traditional suppliers are constrained simultaneously, buyers compete more aggressively for available barrels, and these prices cascade through the U.S. market.
This is why high U.S. crude production does not automatically translate into cheap U.S. diesel. The United States participates in a global market for refined products, and domestic prices reflect both local supply conditions and what buyers elsewhere are willing to pay.
Why not just stop exports?
This naturally raises another question: If U.S. diesel stocks are so low, why allow refiners to export it?
The Trump administration considered restricting diesel exports before President Trump said this week he would do so. not impose a ban. Such a restriction could potentially leave more diesel in the United States and lower domestic prices in the short term, but there would be compromises that complicate the situation.
Refiners optimize the entire barrel, not just one product in isolation. If export restrictions reduce the value of diesel production, refiners could change operating rates or product yields, while foreign buyers would have to replace those U.S. barrels elsewhere. Since gasoline and diesel come from the same refining system, policies aimed at reducing the price of one product can also affect the profitability and availability of the other. Oil markets are interconnected enough that a policy that seems simple in isolation can create second-order effects elsewhere in the system.
The United States can therefore be both the world’s largest producer of crude oil, a major exporter of refined products and a country facing extremely high diesel prices. These conditions are not contradictory; they reflect different stages of the oil supply chain.
Stocks are large
The biggest problem in the short term is inventory. Diesel markets normally contain stored products that provide protection in the event of unexpected refinery shutdowns, increased demand, or disruption of foreign supplies. This cushion has been significantly depleted, leaving the market much more vulnerable to disruptions that would have been easier to absorb under normal conditions.
The EIA expects U.S. distillate inventories to remain exceptionally low through 2027, while seasonal factors could add pressure in the coming months. Refineries typically undergo maintenance in the fall, agricultural demand increases during harvest season, and demand for fuel oil begins to increase as colder weather approaches. When stocks are already low, these routine seasonal changes can have an outsized impact on prices.
Even the end of the Iranian conflict would not immediately restore the market to normal. Oil and diesel prices could certainly fall sharply if geopolitical tensions ease and disrupt refinery production yields, but the world would still need to replenish stocks that were depleted during the crisis.
The EIA estimates that global oil inventories have already declined by about 400 million barrels this year and expects additional declines through the end of 2026. Replacing these inventories requires production to exceed consumption for an extended period, which could keep the market tighter than expected even after the immediate geopolitical advantage disappears.
The real bottleneck
For much of the past decade, discussions about the U.S. energy security focused heavily on crude oil production. The shale revolution has largely solved this problem by allowing U.S. producers to supply huge quantities of oil, but crude production is only one link in a much longer chain.
The current diesel crisis reminds us that energy security also depends on refining capacity, inventories, pipelines, storage terminals, shipping routes and a global network of refineries capable of transforming crude oil into products that consumers actually need. When one of these links becomes restricted, record oil production alone cannot make up for the shortage.
America has no shortage of crude oil. There is a shortage of available diesel. Until global refining production recovers and stocks are replenished, these two conditions may continue to coexist.
By Robert Rapiere
More important reading on Oilprice.com
Gn bussni