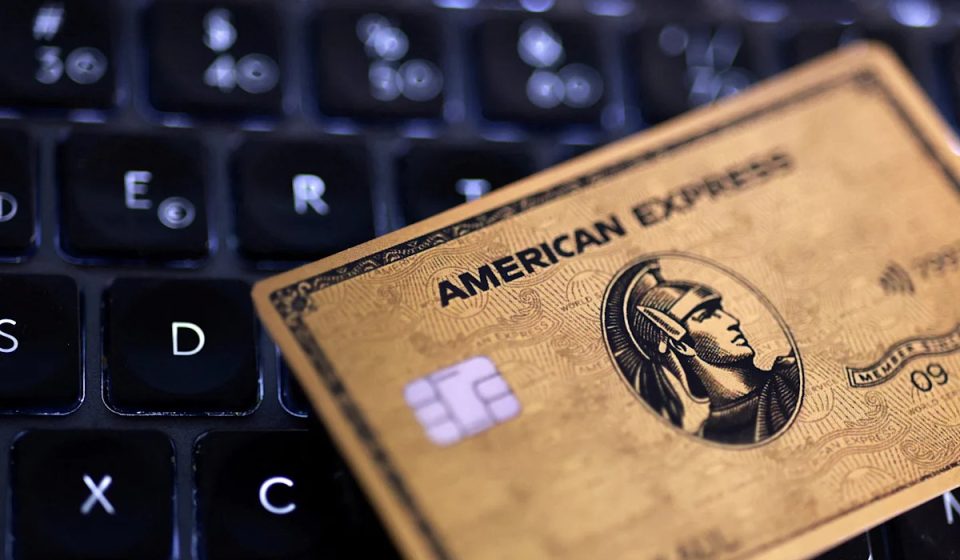

Regulators on Thursday fined American Express (AXP) $350 million for widespread failures in its anti-money laundering controls that left about $13 billion in suspected money laundering activity insufficiently monitored and reported over nearly 11 years.
The Office of the Comptroller of the Currency (OCC) said American Express National Bank failed to maintain adequate safeguards to detect and report suspicious transactions, including potentially illicit activities involving credit and charge cards.
Shares of American Express fell 0.3% in pre-market trading Friday. The stock is down more than 16% since the start of the year.
308.10 +3.85 (+1.27%)
Closing: October 8 at 4:01:55 p.m. EDT
Between June 2014 and May 2025, the bank processed approximately billions in suspected trade-based money laundering activities, including suspicious card charges and chargebacks, according to the OCC order.
Some of these transactions involved accounts associated with bank insiders, the OCC said, although the order did not identify the individuals involved or specify their roles.
American Express said in a statement that it had identified weaknesses in its financial crime compliance program through internal and external reviews.
“We also investigated transactions we identified as being processed on our network by individuals misusing our products to purchase goods and services, reported this information to law enforcement, and took other appropriate action,” the company added.
The company said a portion of the $350 million penalty had already been reserved in previous periods and would not affect its financial guidance for full year 2026. The consent orders do not impose a cap on the company’s assets, and American Express said it also does not expect the costs of complying with them to affect its 2027 guidance.
The agency found that American Express had systemic weaknesses in its monitoring systems, customer identification procedures and internal controls that prevented it from identifying and reporting all suspicious activity to law enforcement.
The bank’s risk assessments focused too much on its relatively limited deposit-taking activities, while failing to adequately consider the risks associated with its much larger credit card and payment businesses, according to the OCC.
Regulators also identified inadequate staffing, insufficient expertise, insufficient employee training and gaps in internal audits that allowed compliance problems to persist.
These failures prevented the bank from providing important information to law enforcement, Comptroller of the Currency Jonathan Gould said in a statement.
Gn bussni