What ice cream has to do with this year’s Nobel Prize in economics: Planet Money: NPR


Royal Swedish Academy of Sciences
This article first appeared in the Planet Money bulletin. You can register here.
On Monday morning, global economics experts listened to a Swedish announcement to find out who won this year’s Nobel Prize in economics. And we had a lesson about… ice cream.
The winners were Robert Hall of Stanford University and Michael Woodford of Columbia University. The prize committee recognized them “for the microeconomic foundations of macroeconomic stabilization.”
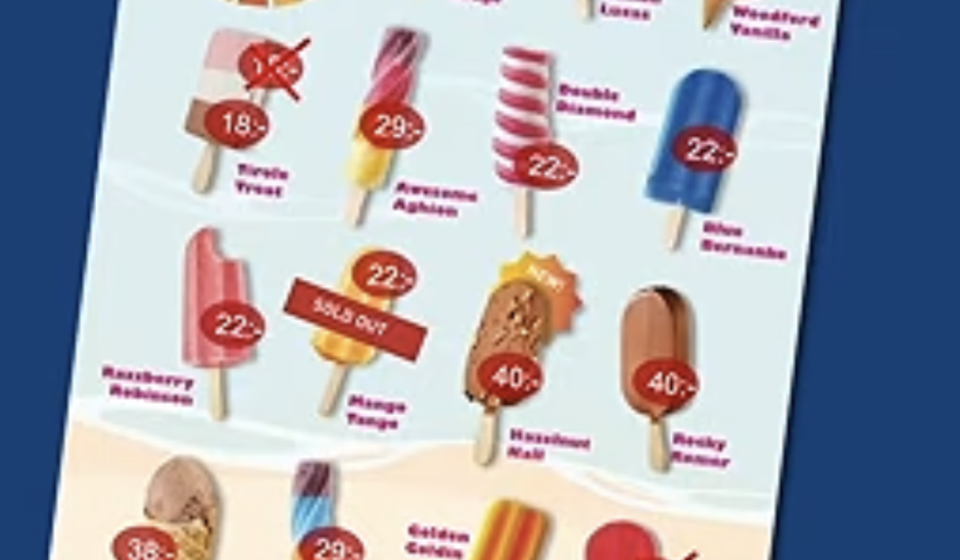
To explain what this means – as we will try to do in this newsletter – Timo Boppart, an economist at Stockholm University and a member of the prize committee, stood up and walked around as if he were giving a TED talk. At one point, he brought up an image on the screen behind him: an ice cream menu.
Boppart used the ice cream menu to serve a sweet lesson in economics.
“How do companies actually set their prices? » » asked Boppart. “This is illustrated here with this ice cream menu. Prices do not adjust (continuously). Rather, companies set the price of this ice cream for an entire season.”
Ice cream was a poetic example. Because prices, like ice cream, can get sticky. In fact, economists use the term “sticky prices” to describe the way in which prices can remain stubbornly stable even when economic conditions change.
This seemingly small detail can have huge consequences for the entire economy. Sticky prices are the cornerstone of what is known as “New Keynesian economics” – a framework that has helped reshape macroeconomic theory and the way policymakers think about fighting recessions and controlling inflation.
This year’s prize recognized work that helped lay the foundations of New Keynesian economics. In doing so, Hall, Woodford and other scholars helped breathe new life into the ideas of economic giant John Maynard Keynes, whose intellectual legacy seemed, for a time, in danger of melting away.
To understand why, we have to go back to the 1970s, when the economy experienced something that, to some, seemed to invalidate Keynesian economics.
Keynesianism freezes
John Maynard Keynes is basically the father of macroeconomics, the study of how the economy as a whole works, including what the government can do to fight recessions, boost employment, and control inflation.
Keynes’ breakthrough came in the depths of the Great Depression, when he published The general theory of employment, interest and money. He formulated an idea that may seem obvious today, but which challenges the economic orthodoxy of his time: an economy can get stuck in a prolonged recession, and the free market will not necessarily put everyone back to work on its own. Instead, Keynes wrote, we needed government to help increase spending, put people back to work, and get the economy healthy.
If you’ve ever taken an Econ 101 course, you’ve probably heard about the “invisible hand” of the free market. This is the idea that individuals and businesses pursuing their own interests in competitive markets can help the economy reach its full potential without government intervention. Keynes essentially argued that we cannot rely on the invisible hand to pull the economy out of the doldrums. We needed the visible hand of government.
Keynes influenced an entire generation of economists and policy makers. Even Milton Friedman, a staunch defender of the free market, is said to have said in 1965: “We’re all Keynesians now.” (He later said the quote had been taken out of context.)
However, by the 1970s, the dominant Keynesian models – and the policies they helped guide – ran into difficulties. Inflation and unemployment rose together – a painful combination known as “stagflation.” Existing Keynesian models struggle to explain it.
“For a long time, Keynes’ recipes seemed to work, but then they failed during the oil crisis of the 1970s, when high unemployment and high inflation took over simultaneously,” John Hassler, chairman of the Nobel committee, said when announcing the prize.
When the old-school models collapsed, some economists wanted to reject Keynes altogether. Economists like Robert Lucas and Edward Prescott – who each won the Nobel Prize – questioned Keynesian economics and its reliance on the ability of government policies to effectively smooth out the ups and downs of the economy. Call it the vengeance of the invisible hand.
A central criticism: Keynesian models rely too much on trends found in past economic data without adequately explaining the individual decisions behind them. Responding to these criticisms meant giving the models “microfoundations”: starting with the decisions of individuals and businesses to explain how the entire economy works. The economy is made up of people, and people anticipate. They anticipate what policymakers will do, and these expectations shape how they spend, save and invest. If policymakers change direction, people’s behavior could also change, making old models an unreliable guide to whether a new policy will work.
An influential alternative to Keynesianism, developed by Prescott and other economists, became known as the “real business cycle” theory. These models assumed that prices and wages were completely flexible, adjusting freely as economic conditions changed. If demand for workers fell, wages could also fall, making workers cheaper to hire and allowing the labor market to balance supply and demand. That left little room for a familiar feature of recessions: people who want to work but can’t find a job.
Gregory Mankiw, now an economist at Harvard University, entered graduate school at MIT alongside Michael Woodford in 1980. They were learning macroeconomics just as economists were struggling to figure out how to rebuild it.
“Lucas and Prescott were ascendant, but many of us were skeptical of their conclusions,” says Mankiw. Planet Money. “And that’s when people like Woodford and Hall came on the scene. The feeling was that those who rejected the Keynesian model were throwing the baby out with the bathwater. And so rather than throwing it out, they wanted to sort of solve the problems.”
A new scoop from Keynes
Hall and Woodford helped rebuild macroeconomics around the decisions of individuals and businesses. Hall broke new ground by understanding how people’s expectations about the future shape their current spending. Woodford built on this work to develop a framework combining forward-looking spending decisions and sticky pricing.
To understand why sticky prices are important, let’s return to the ice cream example. Suppose there is a recession and the demand for ice cream collapses. Stores may not quickly reduce ice cream prices to entice customers to return. Maybe changing menus and signs costs time and money. Or maybe stores don’t yet know whether the drop in demand is temporary or will last. Instead, they keep prices frozen, sell fewer scoops, and might end up having to cut hours or lay people off. When prices don’t adjust, jobs and businesses suffer.
The same story goes for wages, which we believe are a more important factor in the economy than the price of ice cream.
“When economists talk about sticky prices, they also include sticky wages, that is, the price of labor,” says Mankiw. “Most people don’t see their pay adjusted every month.”
Throughout the economy, this rigidity or “price stickiness” can have serious consequences. When spending declines, prices and wages do not adjust quickly and flexibly to incentivize people to buy and businesses to hire. Instead of prices falling to bring supply and demand closer together, in these models price stickiness leads to a decline in output and employment. This helps explain why, during recessions, people who want to work may remain unemployed for long periods of time.
“Bringing these price rigidities into the framework was absolutely essential, because this is why the invisible hand cannot work its magic and there is room for political intervention,” Boppart said during the Nobel announcement.
In other words, even when individuals and businesses anticipate and act in their own self-interest, price stickiness can keep the economy in a recession. Call it the return of Keynes. In these models, governments and central banks still have a role to play in getting the economy back on track.
This was the promise of New Keynesian economics: to take critiques of old models seriously, rebuild models around individual decisions, and preserve Keynes’s central idea that the free market will not always bounce back on its own.
“One thing that clearly differentiates Keynesian models from real business cycle models is price flexibility or stickiness,” says Mankiw. “Most economists today – not all – but I think most economists today adhere to the sticky price hypothesis.”
These new Keynesian models have become an integral part of how governments and central banks plan to fight recessions and control inflation.
Woodford’s work, for example, helped lay the theoretical foundation for forward guidance, a strategy used by the Federal Reserve during the Great Recession. The Fed lowered its benchmark interest rate to near zero, but the economy still needed stimulus. Thus, under Chairman Ben Bernanke, the Fed indicated that it planned to keep interest rates low for an extended period. By shaping expectations about future rates, the Fed has tried to help lower long-term borrowing costs and encourage spending today.
Keynes’s ideas survived thanks to new foundations. And Mankiw offers an update of Milton Friedman’s famous line: “We’re all neo-Keynesians now,” he says.
PS Throughout this article we have referred to this prize as the “Nobel Prize in Economics”. But calling it that is surprisingly controversial. Technically, its name is much clunkier. Economics was not one of the prizes created by Alfred Nobel. So how did he join the club? Ricky and I tell this story in the latest episode of The Planet Money indicator. Find out when it releases on Tuesday.
Gn headline